Conservatory Installers Insurance for conservatory and garden building firms
Conservatory installers insurance for firms with installation teams, a depot or showroom, and jobs that run from the base to the roof. Compare cover for conservatories, orangeries and garden buildings in one place.
- Liability for the build and the house it joins
- Employers' liability for installation teams
- Frames, roof panels and kits covered in transit
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is conservatory installers insurance?
Conservatory installers insurance is cover for firms that build conservatories, orangeries and similar structures at customers' homes and premises. It pairs public and products liability for harm and damage tied to the build, employers' liability for installation teams, and cover for frames and roof panels in transit, tools and work in progress.
Most conservatory firms do more than fit frames. They dig and lay bases, build dwarf walls, tie roofs into the house wall and sometimes run electrics, so one job can involve groundwork, brickwork, glazing and roofing. Claims tend to come from that mix: leaks where the roof meets the house, a drain cracked under the base, or brickwork damaged where a wall plate was fixed.
Many of the same firms put up garden rooms, sheds, garages and carports. Replacement windows and doors are covered on our glaziers insurance page, and full house extensions on builders insurance.
Conservatory installers insurance at a glance
- Suits
- Conservatory, orangery and garden building firms with installation teams
- Core covers
- Public, products and employers' liability with contract works
- Often added
- Goods in transit, tools and plant, showroom and stock
- Insurers ask about
- Bases and groundwork, roof types, electrics and subcontracted trades
- Priced on
- Turnover, wage roll, the trades you carry out and claims
- Separate schemes
- Deposit protection and long-term warranties for homeowners
What does conservatory installers insurance cover?
Conservatory and garden building firms usually combine these sections. Because each job crosses several trades, every activity your teams carry out needs to be declared.
Public liability
Damage at the property during the build, such as a drain cracked while digging the base, a patio broken by a dropped frame, or a roof panel caught by the wind and blown onto a neighbour's car.
Read more about public liability insurance
Products and completed work
Claims after handover, such as water getting into the house at the roof junction, a roof failing under heavy snow, or a garden room door that falls and injures someone.
Read more about products liability cover
Employers' liability
Injuries from lifting glazed units and roof sections, falls from steps and roofs, and cuts and crush injuries during assembly.
Read more about employers' liability insurance
Goods in transit
Frames, sealed units, roof panels and garden building kits carried from your depot to site, against breakage and theft.
Read more about goods in transit insurance
Contract works
A part-built conservatory or garden room, and materials left on the customer's drive, damaged by storm, theft or vandalism before handover.
Read more about contractors' all risks cover
Showroom and depot
Display conservatories and garden buildings, stock in the warehouse, and visitors walking around your show site.
Read more about showroom and premises cover
Tools and plant
Mini diggers, mixers, saws, drills and fixing tools, owned and hired, on site and in vans.
Read more about plant and machinery insurance
More cover installation firms consider
- Professional indemnity: where you design orangeries, specify roof systems or prepare drawings for approval
- Commercial legal expenses: homeowner disputes, unpaid balances and consumer complaints
- Business interruption: lost income if a fire closes your showroom or depot
- Fleet insurance: installation vans and delivery vehicles on one policy
Which installation firms is this for?
Established firms building structures onto homes or in their gardens, from glazed conservatories to timber garages. These are the businesses the cover is usually arranged for.
Garage doors or landscaping? See garage door installers insurance, landscapers insurance or the trades hub.
- Conservatory erectors: uPVC, aluminium and timber conservatories bought from a fabricator and installed by your own teams
- Orangery builders: brick piers, lantern roofs and plastered ceilings, closer to a small extension than a conservatory
- Conservatory roof replacement firms: swapping polycarbonate or glass roofs for solid or tiled systems, which adds weight to the existing frame
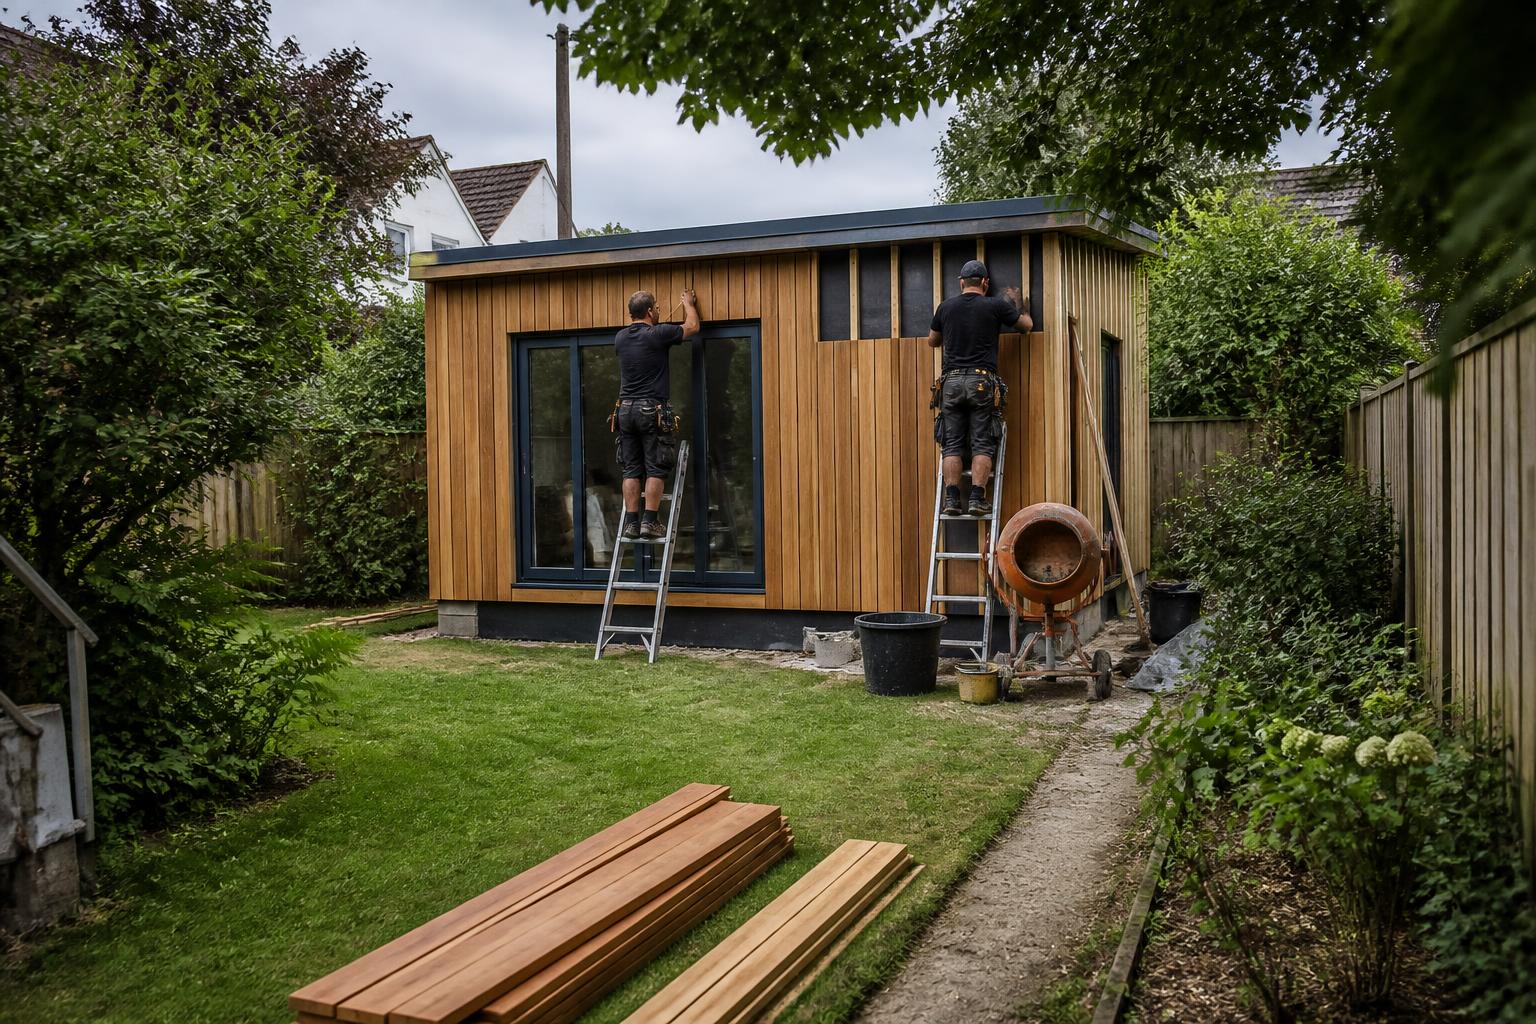
- Garden room and garden office builders: insulated timber buildings, often with electrics and a concrete slab or screw pile base
- Shed and summerhouse installers: delivering and putting up timber and metal sheds, workshops and summerhouses for homes, schools and allotments
- Garage builders: concrete sectional and timber garages, sometimes replacing older garages with asbestos cement roofs
- Carport and canopy installers: carports, veranda canopies and covered walkways for homes, schools and businesses
- Garden building retailers: show sites selling and installing garden buildings, with the retail side often insured under shop insurance
How much does conservatory installers insurance cost?
The range of trades on each job matters as much as turnover. Insurers concentrate on the points below.
Frames only or full build
Firms that also dig bases, build walls and plaster ceilings are rated as a wider building risk than install-only teams.
Roof types
Solid and tiled roof systems, and replacements on existing conservatories, are rated above standard glazed or polycarbonate roofs.
Electrical and other trades
Wiring garden rooms and conservatories is rated separately, and insurers ask whether staff or insured subcontractors carry it out.
Wage roll and subcontractors
Employers' liability follows wages for installers and labour-only workers, while bricklayers and electricians with their own cover are rated differently.
Showroom and stock
Display buildings, stock values and visitor numbers at your show site drive the property and public liability sections.
Claims history
Leaks, roof failures and damage at customers' homes are reviewed closely, along with what changed afterwards.
What conservatory installers insurance does not cover
These gaps cause the most surprise in conservatory and garden building claims.
- Correcting leaks or faults in your own installation, as distinct from the damage they cause
- Customer deposits if your firm closes, which a deposit protection scheme deals with rather than your business insurance
- Electrical work by staff who are not qualified, or work that was not declared
- Removing asbestos from old garages or outbuildings, unless agreed with the insurer
- Design and approval advice, which needs professional indemnity
- Digging beyond the depth limit on your schedule
- Installation vans and delivery vehicles, insured separately on a commercial vehicle policy
Attached to the house or freestanding in the garden?
Most firms build both. Insurers see a conservatory tied into a house differently from a building at the end of the garden, so describe the split accurately.
| Feature | Conservatories and orangeries | Garden buildings, garages and carports |
|---|---|---|
| Where claims arise | The junction with the house wall, roof leaks and damage inside the home | Bases, drains, fences and boundaries |
| Link to the house | Tied into existing brickwork, with fixings into walls and lintels | Usually standalone, on a slab, piles or timber frame |
| Common extra trades | Bricklaying, plastering, electrics and heating | Groundwork, and electrics for garden rooms |
| Completed work claims | Water getting into the house, and roofs failing under load | Roof felt failures, snow loading and doors or fittings giving way |
| Insurer questions | Roof type, solid roof replacements and work on existing walls | Base type, lifting arrangements and asbestos in old structures |
How to compare conservatory installers insurance
Brokers place installation firms faster when they can see the full spread of work.
Break down each type of job
Frames only, full builds with bases and walls, roof replacements, garden buildings, garages and carports.
List your teams
Employed installers, labour-only workers and subcontracted bricklayers, plasterers and electricians.
Value showroom and stock
Display buildings, warehouse stock and the busiest times of year.
Describe vehicles and transit
How many vans carry frames and panels, how they are secured and the value on each.
Collect claims and complaints
Past claims and customer complaints, with the cause and what you changed.
Quotes for conservatory and garden building firms
Describe the structures you build and the trades you use, and a broker who knows home improvement firms will compare terms.
Compare coverConservatory installers insurance FAQs
How much does conservatory installers insurance cost?
Turnover, wage roll, whether you build bases and walls, roof types, electrical work, showroom values and claims history set the price. A firm fitting frames on bases built by others is rated differently from one delivering complete orangeries, and a broker can show where the cost sits.
Does conservatory installers insurance cover sheds, garages and carports?
It can, if you declare them. Many conservatory firms also put up sheds, garden rooms, garages and carports, and insurers usually add these to the same policy. Groundwork, electrics and asbestos removal on these jobs need to be described as well.
Are leaks where the conservatory meets the house covered?
Water damage to the home and its contents caused by a faulty junction is normally a completed work claim. Resealing or rebuilding the junction itself is usually your cost, as policies do not pay to put right your own workmanship.
Is replacing a conservatory roof with a solid roof covered?
Yes, if declared. Solid and tiled roof replacements put more weight on the existing frame and base, so insurers ask whether you check the structure first and use an approved system. Undeclared roof replacement work could leave a claim unpaid.
Do we need cover for the electrics in garden rooms?
If your teams wire garden rooms or conservatories, declare it and confirm the staff are qualified. If an insured electrical subcontractor does the work, keep a copy of their insurance, because your policy may not respond to their mistakes.
Are customer deposits protected by our business insurance?
No. Business insurance covers injury, damage and your property, not the money customers have paid if your firm stops trading. Deposit protection and insurance-backed warranties come from separate providers, often linked to trade bodies.
Does the policy cover removing an old asbestos garage?
Many policies exclude asbestos work. Older prefabricated garages often have asbestos cement roofs, so insurers expect a check before demolition and specialist removal where it is found. Tell the broker if your teams dismantle old structures.
Can replacement windows and doors go on the same policy?
Often, yes. Many conservatory firms also fit windows and doors, and insurers can add that work if it is declared with its share of turnover. Firms where glazing is the main business are usually rated as glaziers, with bases, walls and garden buildings added as extra activities.
How do I get a conservatory installers insurance quote?
Ask for a quote through the form here, and a home improvement trades specialist will ring you back. Have your job types, payroll, subcontractors, showroom and stock values, vehicles and claims history ready.
Ready to compare conservatory installers insurance?
Cover for conservatory, orangery and garden building firms, from the base to the roof and every trade in between.