Wholesale and Distribution Insurance for stockholding businesses
Cover for wholesalers, importers and distributors holding significant stock and moving it every day. Compare policies through specialist brokers who understand stock declarations, warehouse risks and customer credit.
- Stock cover that follows seasonal peaks
- Goods in transit and import cargo arranged together
- Products liability for goods you import or supply
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is wholesale and distribution insurance?
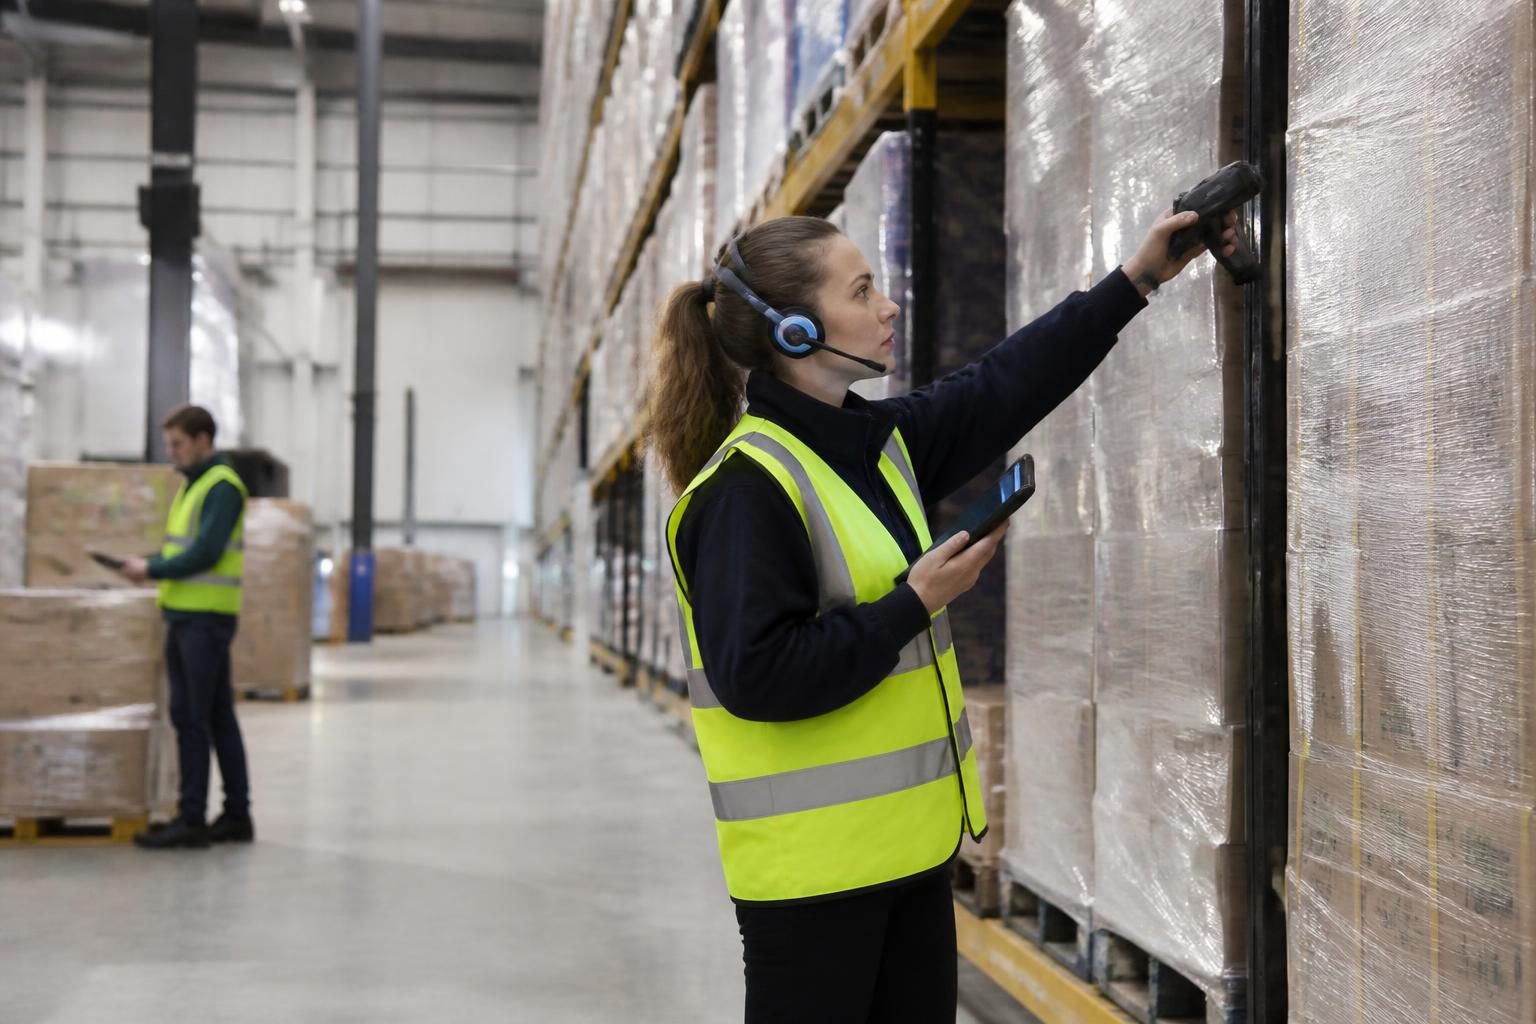
Wholesale and distribution insurance protects businesses that buy, store and sell goods on to other businesses. It usually combines cover for stock and premises, the profit lost after damage, goods in transit and liability for staff, visitors and the products supplied, often with trade credit for unpaid invoices.
Stock is normally the largest value on the schedule, and it rarely stays still. Policies can be set up so the sum insured rises for busy periods, or so you declare actual stock values at agreed intervals and pay premium on what you really held. Stock at ports, third-party stores and customers' premises can be added.
Importers carry a products risk close to a manufacturer's. A business that brings goods into the UK can be treated as the producer of a defective product, and claimants often pursue the importer because the overseas maker is hard to reach, so supplier vetting, contract terms and your products liability limit sit at the centre of the programme.
Wholesale and distribution insurance at a glance
- Typical buyers
- Wholesalers, importers, cash and carry operators and distribution businesses
- Largest exposure
- Stock values, often concentrated in one or two large buildings
- Must have
- Employers' liability where you employ staff
- Common additions
- Goods in transit, marine cargo, trade credit and fleet
- Underwriters focus on
- Storage height, sprinklers, security, theft-attractive lines and import sources
- Stock options
- Seasonal increases or a declaration basis linked to actual values
Which policies do wholesalers and distributors combine?
A distribution programme follows the goods: from the supplier, into the warehouse, onto vehicles and out to customers. These are the covers a broker usually brings together.
Stock and contents
Goods for resale, racking, handling equipment and office contents at each depot, against fire, flood, theft and accidental damage. Theft-attractive lines such as alcohol, tobacco, electronics and pharmaceuticals carry their own security terms.
Read more about a commercial combined policy
Warehouses and depots
Buildings you own or lease, including loading docks, canopies and yard areas. Many leases pass the duty to insure to the tenant, so the lease is worth checking alongside the schedule.
Read more about warehouse insurance
Business interruption
Lost gross profit if a fire or flood takes a depot out of action, plus the extra cost of renting space, hiring staff and rerouting deliveries. Cover can extend to damage at a key supplier or a third-party store.
Read more about business interruption cover
Goods in transit
Loads on your own vehicles and those sent by carrier or courier, including theft from parked vehicles, subject to the security conditions the insurer sets.
Read more about goods in transit insurance
Marine cargo
Imports and exports by sea, air and road from the supplier's door to yours, with the point at which you take on the risk set by the shipping terms in each contract.
Read more about marine cargo insurance
Products liability
Injury or damage caused by goods you import, own-brand or distribute. Insurers ask where products are made, who tests them and whether you can pass a claim back to the supplier.
Read more about products liability insurance
Employers' and public liability
Claims from warehouse staff, drivers and visitors, with forklift, racking and manual handling incidents the usual sources. Employers' liability is compulsory for most firms with employees.
Read more about employers' liability insurance
Trade credit
Pays out when a customer becomes insolvent or fails to pay within agreed terms, and can support better funding terms against your debtor book.
Read more about trade credit insurance
Crime and fidelity
Theft of stock or money by employees, and frauds such as false supplier bank details, which property sections rarely pick up.
Read more about crime and fidelity cover
Other covers distributors often need
- Fleet insurance: lorries, vans and cars under one motor policy, with forklifts that use public roads added
- Product recall: withdrawing a contaminated or unsafe batch from customers and shelves
- Cyber insurance: outages of warehouse management, ordering and online sales systems
- Engineering inspection: thorough examinations of forklifts, goods lifts and dock levellers
- Legal expenses: contract and debt disputes with customers and suppliers
Which wholesale and distribution businesses do we cover?
Underwriters look first at what you hold and how attractive it is to thieves, then at how it is stored and moved. These are the sub-sectors most often placed.
Hauling for other firms too? Carrying other people's goods for payment needs different motor and transit cover. See haulage and logistics insurance or all industries.
- Food and drink wholesalers: chilled and frozen stock where refrigeration breakdown and spoilage cover matter
- Cash and carry operators: trade customers on site every day, high value stock and cash handling
- Builders' and timber merchants: yards, timber stores and heavy goods delivered to sites
- Electrical and plumbing wholesalers: trade counters, plus cable and copper stock that attracts metal theft
- Importers of consumer goods: products from overseas factories, where you can be treated as the producer
- Pharmaceutical and healthcare distributors: temperature-controlled stock and strict batch traceability
- Fashion and textile wholesalers: seasonal peaks and goods held at third-party stores
- Electronics and technology distributors: compact, high value stock with tight security conditions
- Alcohol and tobacco distributors: theft-attractive stock where alarms, vaults and yard security are reviewed closely
- Automotive parts distributors: wide ranges, frequent deliveries and parts fitted to customers' vehicles
- Online fulfilment centres: stock held for many clients and systems running around the clock
- Third-party logistics providers: customers' goods held under contract terms that set your liability
- Agricultural and garden suppliers: fertilisers, chemicals and seasonal ranges with pollution exposure
- Stoneware wholesalers: stoneware tableware, planters and garden pots stored on pallets and racking, where breakage in handling and transit, and heavy loads on racking, are the main questions
- Packaging and janitorial suppliers: bulky combustible stock and regular deliveries to business customers
How much does wholesale and distribution insurance cost?
The premium follows the goods: how much you hold, what it is, where it sits and how it travels. These are the points underwriters weigh.
Type of stock
Alcohol, tobacco, electronics, metals and branded clothing attract thieves and are priced accordingly. Bulky, low value goods sit at the other end.
Storage and fire protection
Racking height, sprinklers, detection, forklift battery charging areas and how stock is separated from offices all shape the property rate.
Security
Monitored intruder alarms, perimeter fencing, CCTV, yard lighting and how keys and loaded trailers are controlled overnight.
Stock values and peaks
Average and maximum stock, how far values swing through the year and whether you choose a declaration basis.
Transit and import exposure
The value of each load, how vehicles are secured, the carriers you use and the countries goods come from.
Products and credit risk
Where products are made, your quality checks, turnover by product line and the credit you extend to customers.
Common exclusions for stockholding businesses
Distribution claims are often reduced by conditions rather than refused outright. Check these gaps before a loss.
- Theft from unattended vehicles that do not meet the security terms in the transit policy
- Stock left in the open yard or in parked trailers, unless specifically agreed
- Deterioration of chilled or frozen stock, unless refrigeration breakdown cover is added
- Shortages found at a stock count with no identifiable cause
- Customers' goods held in storage, which need warehousing liability cover rather than your own stock section
- Bad debts, which only trade credit insurance covers
- Underinsured stock, where values at the time of loss exceed the sum insured or the last declaration
Your own stock or other people's goods?
Distributors who also store goods for clients need two different kinds of cover. This is how a wholesale policy compares with warehousing and storage cover.
| Feature | Wholesale policy | Warehousing and storage cover |
|---|---|---|
| Whose goods | Stock you own and sell on | Goods owned by customers and held under contract |
| What it pays for | Your own loss of stock and profit | Your liability to customers for their goods |
| Key document | Your stock records and sum insured | The storage terms agreed with each customer |
| Typical additions | Transit, cargo, trade credit and products liability | Handling liability and customers' goods in transit |
| Usually suits | Wholesalers, importers and cash and carry | Third-party logistics and contract warehousing |
How to compare wholesale and distribution insurance
Clear figures on stock and transit save time with underwriters. These are the steps a broker will take you through.
Map your stock
Each site, average and peak values, theft-attractive lines and any stock held at ports or third-party stores.
Describe storage and security
Building construction, racking heights, sprinklers, alarm monitoring and yard arrangements.
Set out how goods move
Own vehicles, carriers, couriers, import routes and the largest single load you send.
Review supplier and customer terms
Where products come from, the indemnities you give and receive, and the credit terms you offer.
Compare conditions as well as cover
Security requirements, declaration rules, transit conditions and excesses can matter more than the headline limit.
Speak to a distribution specialist
Share your stock, sites and transit details and a specialist broker will compare cover for you.
Get a quoteWholesale and distribution insurance FAQs
How much does wholesale insurance cost?
It depends on the type and value of stock, how it is stored and protected, security, transit exposure, imports, turnover and claims history. Theft-attractive lines and large concentrations of stock in one building weigh most heavily. A broker can show how each section contributes to the premium.
What is a stock declaration policy?
It is a way of insuring stock where you agree a maximum figure and then declare actual values to the insurer at set intervals. The premium is adjusted to what you really held, which suits businesses whose stock rises and falls sharply through the year.
Am I liable for products I import but do not make?
Often, yes. A business that imports goods into the UK can be treated in the same way as the manufacturer if a product proves defective, and it is usually the easier party for a claimant to pursue. Insurers ask about suppliers, testing and contracts before setting your products liability terms.
Does my policy cover goods while they are being delivered?
Only if transit cover is included. Many combined policies give a modest amount, but regular deliveries or high value loads usually need a dedicated goods in transit policy, with security conditions your drivers can meet in practice.
Are imports covered before they reach my warehouse?
Not under a standard property section. Goods travelling from overseas suppliers need marine cargo cover, and whether you or the supplier arranges it depends on the shipping terms agreed in each contract.
Do I need different cover for goods I store for customers?
Yes. Your stock section covers goods you own. Goods held for others need warehousing liability cover, and the limits depend on the storage terms agreed with each customer, so those terms are worth reviewing with the broker.
Are forklift trucks covered?
On site, damage to forklifts can sit under the property or equipment section and injuries under liability. Thorough examinations can be arranged through engineering inspection. Any forklift driven on a public road also needs motor insurance.
Can trade credit insurance cover all my customers?
Most policies cover the whole debtor book, with the insurer setting a credit limit for each buyer, though some insurers will cover key accounts only. The limits on offer depend on your customers' financial strength and your own credit control.
How do I get a wholesale and distribution insurance quote?
Send your details through this page and a broker who places distribution risks will pick it up. Stock values by site, storage and security details, transit and import routes, turnover, wage roll and claims history are what they work from.
Ready to compare wholesale and distribution cover?
Stock, transit, products and credit risk brought together by a broker who works with stockholding businesses.