Fireplace Installers Insurance for stove and fireplace firms
Fireplace installers insurance for stove and fireplace businesses with showrooms, fitting teams and chimney engineers working in homes and commercial buildings. Compare cover built for a trade whose work is lit up the day after it is finished.
- Liability for chimney fires, smoke and fumes
- Showroom, display stock and stone surrounds insured
- Employers' liability for fitters working on roofs
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is fireplace installers insurance?
Fireplace installers insurance is cover for businesses that supply and fit stoves, fireplaces, flues and chimney liners. It combines public and products liability for fire, smoke and fume damage or injury caused by your work or the appliances you sell, with employers' liability for fitters, and cover for showroom premises and stock.
The serious claims in this trade start in the chimney. A liner joint left open, a stove too close to a timber beam or a register plate not sealed can lead to a chimney fire, a house fire or fumes entering a bedroom. Insurers look closely at thatched and timber-framed properties, where a single install carries much more risk.
Many fireplace firms also run a showroom, cut and fit stone or marble surrounds, and sweep or repair chimneys, so the policy needs to reflect all of it.
Fireplace installers insurance at a glance
- Suits
- Stove and fireplace firms with fitters, showrooms and vans
- Core covers
- Public and products liability, employers' liability, premises and stock
- Main claim types
- Chimney fires, fumes, scorching of timbers, damage during fitting
- Insurers ask about
- Competent person scheme membership, thatched properties, roof work
- Priced on
- Install volume, fuel types, showroom values, wage roll, claims
- Gas fires
- Covered on our gas fitters insurance page
What does fireplace installers insurance cover?
Fireplace businesses usually combine the sections below. Fire and fumes run through the liability sections, so check the limit and any conditions on chimney checks.
Fireplaces
Damage and injury from fireplaces you open up, line and fit, from scorched lintels and beams to fires spreading into floor voids.
Read more about public liability insurance
Stoves
Claims after a wood burner or multi-fuel stove you supplied or installed is lit, such as fumes from a poor flue connection or heat damage to nearby combustibles.
Read more about products liability insurance
Chimneys and liners
Lining, capping and repairing chimneys, where a failed liner or blocked flue can cause a chimney fire or let smoke into adjoining homes.
Fumes and carbon monoxide
Injury claims from occupants exposed to fumes from a solid fuel appliance or flue you installed, swept or inspected.
Fitters and roof work
Employers' liability for staff hurt carrying heavy stoves and surrounds, working on roofs and stacks, or breathing soot and dust.
Read more about employers' liability insurance
Showroom and display stock
Stoves, fire surrounds, tools and accessories at your showroom and stores, with cover for the premises themselves.
Read more about commercial property insurance
Live displays
Working stoves in the showroom bring a fire risk of their own. Insurers ask how displays are flued, supervised and put out at closing time.
Stone and marble work
Cutting and polishing stone surrounds and hearths in a workshop, including machinery, dust control and damage to stone in transit.
Read more about business equipment insurance
Other covers fireplace firms consider
- Business interruption: lost profit if fire or flood closes the showroom
- Goods in transit: stoves and stone surrounds carried from suppliers and to customers
- Commercial legal expenses: disputes over installs, deposits and customer complaints
- Professional indemnity: for firms that survey chimneys or advise on suitable appliances
Which fireplace businesses need this cover?
It suits established firms whose teams install or service heating appliances that burn fuel in an open fire or stove. Typical buyers include the following.
Fitting gas fires as well? Gas appliances need registered engineers; the risks are set out on gas fitters insurance. For other trades, see the trades hub.
- Stove installers: wood burning and multi-fuel stoves for homes, holiday lets and rural businesses
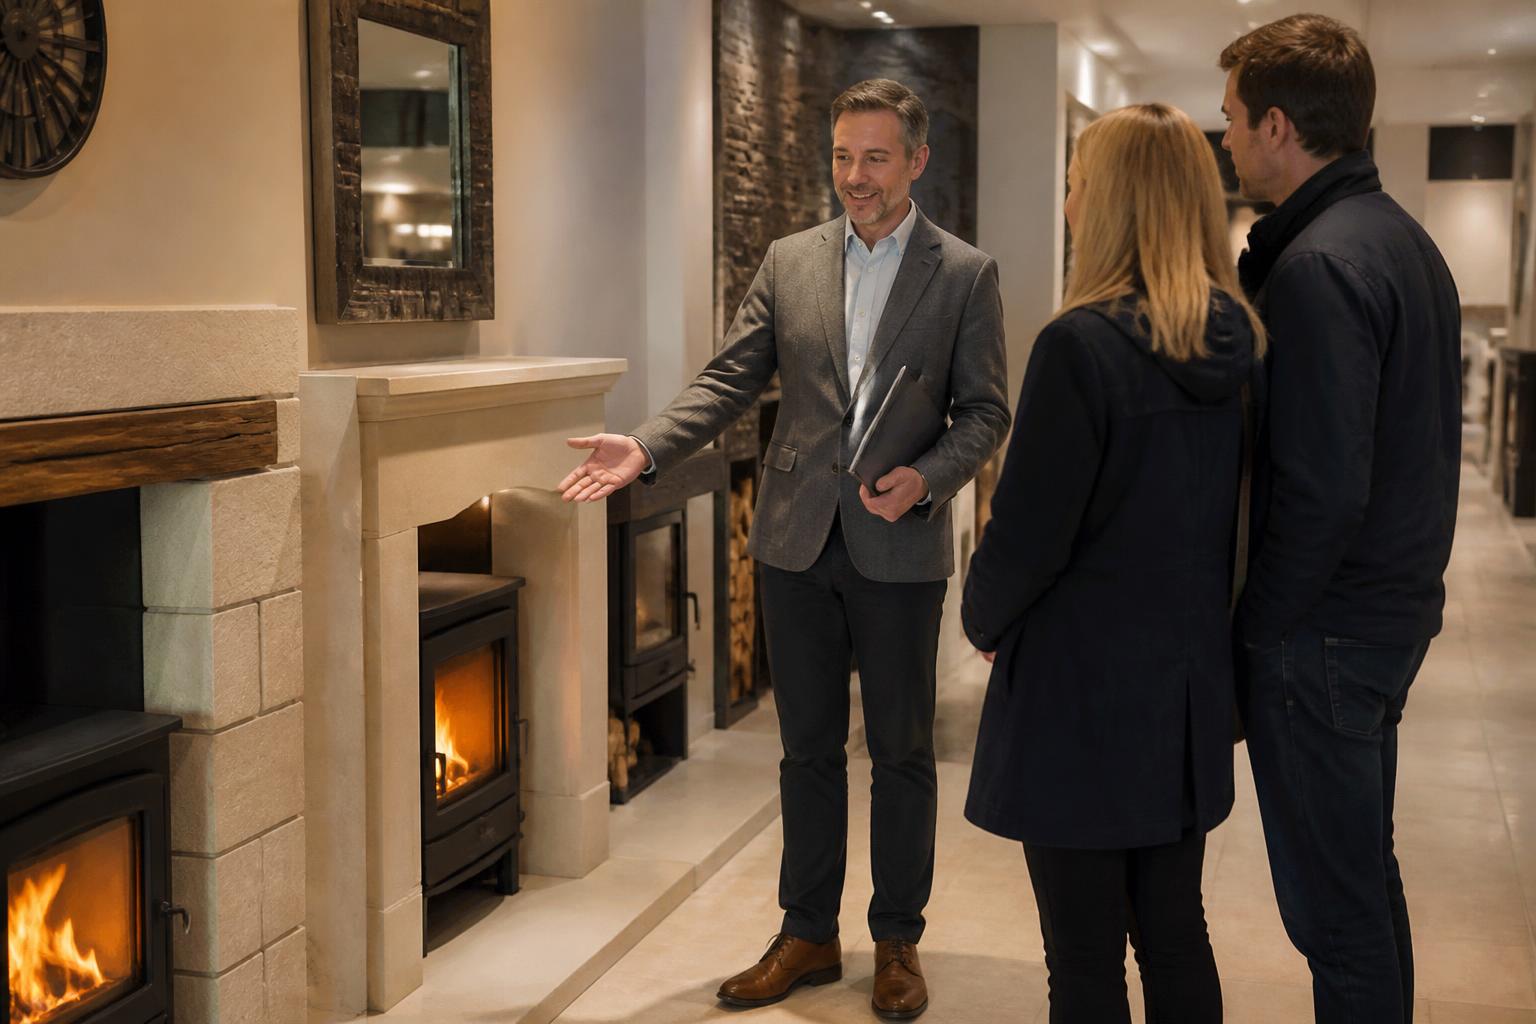
- Fireplace showrooms with fitting teams: retail showrooms that sell, survey and install, often across a wide area
- Chimney lining and repair specialists: liners, cowls, pots and stack repairs, often alongside roofing work
- Chimney sweeps with staff: sweeping, inspection and smoke testing for homeowners, landlords and letting agents
- Fire surround makers: stone, marble and timber surrounds made in a workshop and fitted on site
- Electric fire and media wall installers: electric and bioethanol fires and built-in media walls, with wiring often handled by electrical contractors
- Restoration and period fireplace firms: reclaimed fireplaces in older and listed buildings
- Builders offering fireplaces: refurbishment firms opening up fireplaces as part of wider work under builders insurance
How much does fireplace installers insurance cost?
Insurers price a fireplace business on what it fits, where it fits it and how it checks the chimney first. These are the main factors.
Install volume and type
The number of stoves, fireplaces and liners fitted each year, and the split between solid fuel, electric and other fuels.
Property types
Thatched roofs, timber frames and listed buildings increase the fire risk insurers see and may carry extra conditions.
Chimney checks
How you survey, sweep and smoke test a chimney before fitting, and the records you keep, count for a lot.
Scheme membership
Membership of a competent person scheme for solid fuel, and the training your fitters hold, reassures insurers.
Showroom and stock
Premises, display stock and live burning displays set the property part of the premium.
Claims history
Chimney fires, fume complaints and heat damage claims weigh heavily, along with what you changed afterwards.
What fireplace installers insurance usually excludes
These are the gaps that catch fireplace firms out when they claim.
- Gas fires and gas appliances fitted without a registered engineer, which are dealt with on our gas fitters page
- Replacing your own faulty liner, hearth or flue connection, as opposed to the damage it causes
- Installs in thatched properties that were not declared or did not meet the insurer's conditions
- Work at height beyond the declared limit, or roof work without suitable access
- Asbestos disturbed in old flue pipes, fire backs or boards without the right checks
- Advice on whether a chimney or appliance is suitable, unless professional indemnity is held
- Delivery vans and fitters' vehicles while being driven, insured separately under commercial vehicle insurance
Selling from a showroom or fitting the stove: what changes?
Many fireplace businesses do both. Insurers treat a supply-only sale very differently from an install your team carries out.
| Feature | Supply only | Supply and install |
|---|---|---|
| Main liability | The appliance or surround you sold | The install, the flue and the chimney |
| Typical claim | A faulty stove or part | Chimney fire, fumes or heat damage |
| Who fits it | The customer's own installer | Your team, under your scheme membership |
| Key cover | Products liability and showroom property | Public and products liability and employers' liability |
| Insurer questions | Where products are sourced and how they are labelled | Chimney checks, clearances and sign-off |
How to compare fireplace installers insurance
Fireplace work is underwritten on detail. Have this ready before you ask for quotes.
Split your turnover
Show showroom sales, solid fuel installs, chimney lining and repairs, sweeping and electric fires.
Describe your checks
Explain how chimneys are surveyed, swept and smoke tested, and what is recorded at sign-off.
Note special properties
Say how many installs are in thatched, timber-framed or listed buildings.
Value premises and stock
Showroom rebuild cost, display stock, stone in the workshop and stock in vans.
List staff and claims
Fitters, sweeps and showroom staff, wage roll, and any fire or fume incidents with what changed.
Quotes for fireplace firms
Tell us about your showroom, fitting teams and the appliances you install, and a broker will look for suitable terms.
Get a quoteFireplace installers insurance FAQs
How much does fireplace installers insurance cost?
It depends on your install volume, the fuels and appliances you fit, the properties you work in, how you check chimneys, your showroom values, wage roll and claims. A firm fitting stoves in thatched cottages is rated differently from one selling electric fires.
Does fireplace installers insurance cover a chimney fire after an install?
Usually, yes, if your work caused it. Products and public liability respond to fire damage to the property and injury to occupants, subject to the limit and any conditions on chimney checks. Replacing your own liner is normally excluded.
Are stoves, fireplaces and chimneys all covered on one policy?
They can be. Most fireplace policies cover stove installs, opening up and fitting fireplaces, and chimney lining or repair, provided each activity is declared. Roof work on stacks is often rated separately because of the height involved.
Do insurers need us to be in a competent person scheme?
Many insurers ask about it. In England and Wales a solid fuel install usually needs building control sign-off, which members of a competent person scheme can self-certify; Scotland and Northern Ireland have their own approval routes. Membership and training records show insurers that installs are checked.
Are installs in thatched properties covered?
Often, but they must be declared. A thatched roof makes a chimney fire far more serious, so insurers may ask about liner type, flue temperatures, spark arrestors and the checks made before fitting.
Is our showroom with lit stoves covered?
Yes, as part of the premises section, provided live displays are declared. Insurers ask how the display stoves are flued, who supervises them and how they are made safe at the end of the day.
Can chimney sweeping be added to the policy?
Yes. Sweeping, inspection and smoke testing can be added as declared activities. A sweep who misses a defect may face a claim after a fire, so records and photographs of each sweep are worth keeping.
Are gas fires covered by fireplace installers insurance?
Only if you employ registered gas engineers and declare the work. Gas fires carry the specific risks of gas escapes, so many fireplace businesses insure that part through cover designed for gas engineering firms.
How do I get a fireplace installers insurance quote?
Enquire through this page; a broker familiar with stove and fireplace businesses will then get in touch. Your turnover split, install numbers, chimney checks, showroom values and any fire or fume claims let them go to market quickly.
Ready to compare fireplace installers insurance?
Liability, showroom and fitting cover for stove and fireplace businesses, arranged by a broker who understands chimney risks.