Landscapers Insurance for design and build landscaping firms
Landscapers insurance for firms that design and build gardens, public spaces and hard landscaping schemes with their own crews, plant and nursery stock. Compare cover for the structures you build, the designs you draw and the planting you are paid to establish.
- Liability for walls, decking and water features you build
- Contract works for hard and soft landscaping in progress
- Professional indemnity for garden and landscape design
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is landscapers insurance?
Landscapers insurance is cover for firms that design and build gardens, courtyards, public realm and commercial landscapes. A typical policy sets public and employers' liability alongside contract works, plant, tools and professional indemnity, and is shaped around landscaping risks: retaining walls, decking and water features that fail, struck services, altered drainage and design mistakes.
This page is for landscape construction, meaning new schemes and projects. Recurring mowing, hedge and site upkeep contracts are covered on our grounds maintenance insurance page, and firms that only lay drives and patios on driveway and patio installers insurance.
Landscapers insurance at a glance
- Suits
- Design and build landscapers and commercial landscape contractors
- Core sections
- Public and employers' liability, contract works, plant, tools and design
- Compulsory part
- Employers' liability for landscape crews and labour-only gangs
- Key questions
- Design work, wall heights, water features, tree work and highway work
- Priced on
- Turnover, wage roll, contract values, design fees and claims
- Separate cover
- Tippers, crew vans and trailers on a fleet policy
What does landscapers insurance cover?
Most landscaping policies are assembled from the sections below. Living plants, structures and design are where policies differ most, so compare those closely.
Public liability
Injury and damage while you work, such as a neighbour's fence pushed over by spoil, a gas pipe cut while digging a tree pit or a visitor tripping over materials on a public realm scheme.
Read more about public liability insurance
Products and completed works
Claims after handover, such as a retaining wall that collapses, raised decking that gives way or a child hurt at a water feature you built.
Read more about completed works cover
Employers' liability
Injury and illness among crews, including lifting stone and sleepers, cutting dust, vibration from breakers and compactors, and plant accidents.
Read more about employers' liability insurance
Contract works
Hard and soft landscaping being built, plus materials on site, against storm, flood, vandalism and theft. Many policies limit cover for trees and plants, so living material is worth checking.
Read more about contract works insurance
Landscape design
Garden designs, planting plans, levels and retaining wall details that cause a client loss, such as a scheme that floods or a wall that must be rebuilt.
Read more about professional indemnity insurance
Plant
Mini diggers, dumpers, tracked barrows and turf cutters, owned or hired in, on site and on trailers.
Read more about plant and machinery cover
Tools and equipment
Saws, splitters, compactors, laser levels and hand tools in vans, at the yard and on site.
Read more about tools and equipment insurance
Nursery stock and materials
Plants, trees, stone and timber held at your yard or nursery before use, against theft, fire and storm.
Street furniture installation
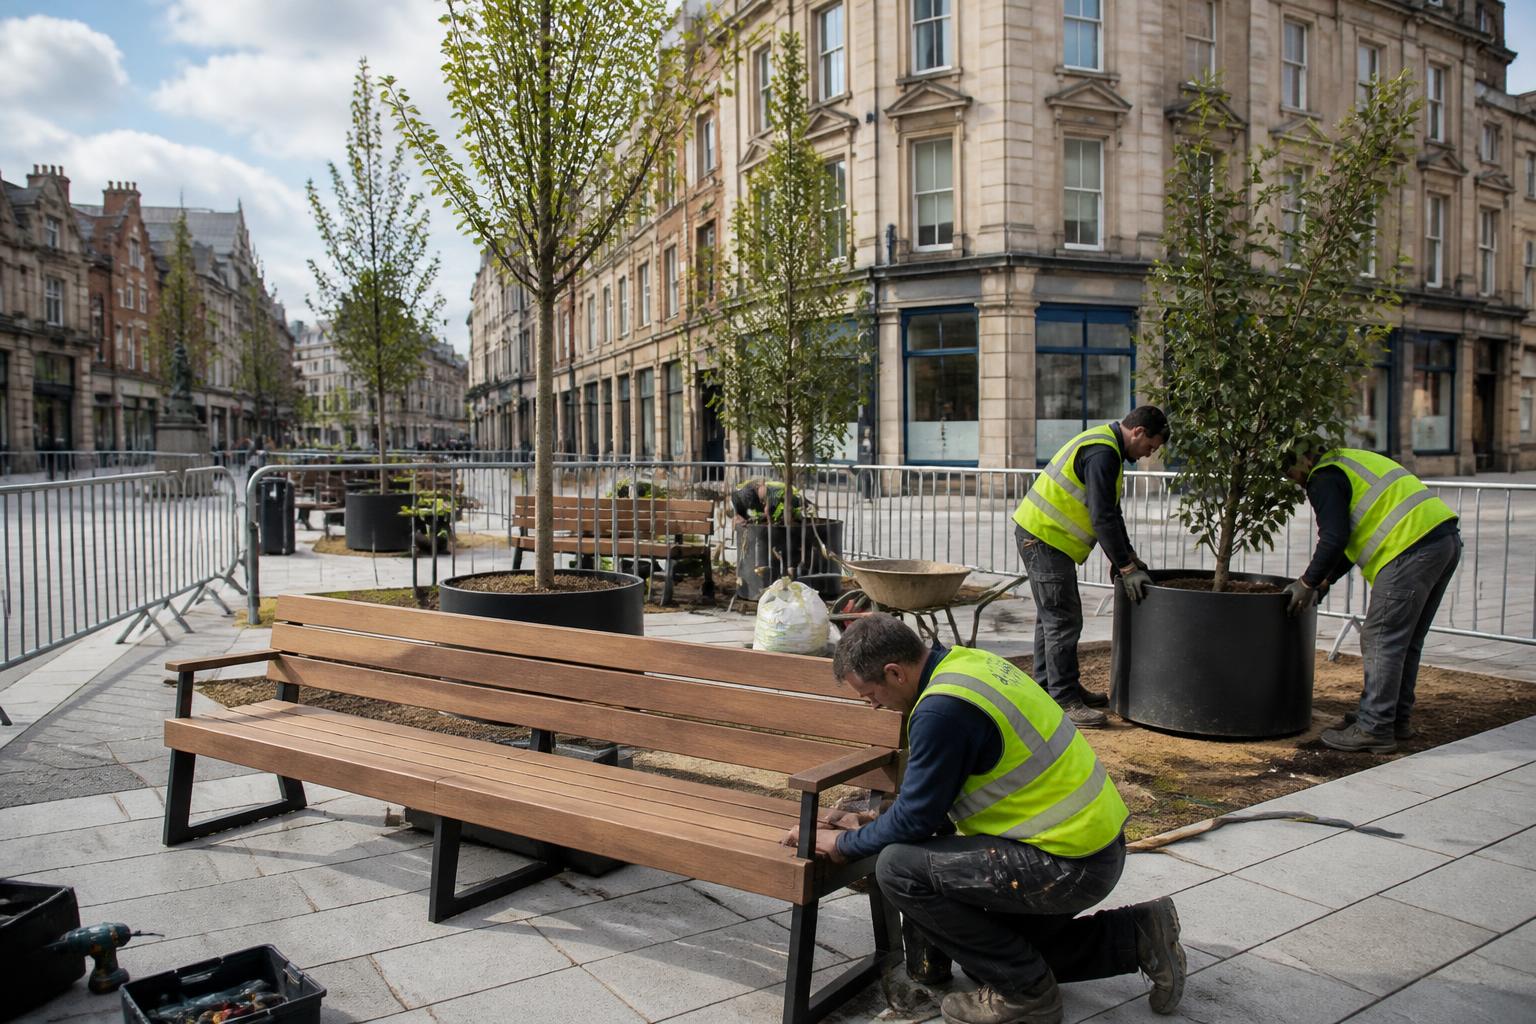
Benches, bollards, cycle stands, planters and signs fixed on public realm and highway schemes, including claims if an item you installed comes loose or fails.
Other cover landscaping firms add
- Tree surgery extension: felling, climbing and work at height are often excluded unless declared and agreed
- Commercial vehicle insurance: for tippers, crew vans and plant trailers
- Commercial legal expenses: disputes over final accounts, variations and failed planting
- Environmental liability: herbicide, fuel and silt pollution on larger schemes
Which landscaping firms is this cover for?
Landscaping runs from private gardens to town centre schemes. These are the firms we see, many of them working across several areas.
Looking after sites once built? Recurring upkeep work has its own grounds maintenance insurance page. Other trades are listed on our trades hub.
- Garden design and build firms: private gardens for homeowners, from design through to planting and handover
- Commercial landscape contractors: landscaping for housebuilders, business parks, schools and commercial landlords
- Hard landscaping contractors: paving, walling, steps, retaining structures and decking within larger landscape schemes
- Public realm landscapers: town centre, park and highway schemes for councils and civil engineering contractors
- Street furniture installation firms: benches, bollards, shelters, cycle stands and planters fixed in streets and public spaces
- Soft landscaping specialists: tree planting, turfing, planting schemes and establishment periods
- Water feature and pond builders: ponds, rills, fountains and natural swimming ponds
- Green roof and living wall installers: planted roofs and walls on commercial buildings, where work at height comes into play
How much does landscapers insurance cost?
Landscapers are priced on how much they design, what they build and where. Insurers focus on the points below.
Design responsibility
Firms that design schemes, levels and structures add professional indemnity, which insurers rate on design fees and the kind of work involved.
Hard and soft split
Walls, paving, structures and plant work carry more liability weight than planting and turfing.
Structures you build
Retaining walls, raised decking, water features and garden buildings attract questions on design, foundations and handover.
Public realm and highway work
Street furniture and work in the highway bring traffic, the public and contract liability limits into the rating.
Plant and tools
Owned plant values, hire spend and overnight security on trailers and in vans affect the premium.
Claims history
Wall failures, service strikes and theft claims are reviewed, along with how procedures have changed since.
What landscapers insurance does not usually cover
These exclusions catch landscaping firms out more than any others.
- Replacing plants, trees or turf that fail to establish because of drought or poor aftercare
- Rebuilding your own faulty walls, paving or decking
- Design errors, unless professional indemnity has been added
- Tree felling and work at height, unless declared and accepted by the insurer
- Herbicide damage where spraying was not declared, operators lacked the certificates the policy asks for or products were not used as their labels allow
- Gradual pollution, which sits under environmental liability cover
- Tippers, crew vans and road-going plant once travelling on public roads, which need fleet or vehicle cover
Hard landscaping or soft landscaping: how the cover differs
Most schemes include both, but insurers rate them differently. Knowing your split helps when comparing quotes and setting limits.
| Feature | Hard landscaping | Soft landscaping |
|---|---|---|
| Typical work | Walls, paving, steps, decking, edging and street furniture | Planting, turfing, tree planting and seeding |
| Main liability risk | Struck services, failing structures and damage to neighbouring property | Herbicide drift, tree work and trips over materials |
| After handover | Collapsed walls, loose paving and failed decking | Trees that later fall, or roots that reach foundations and drains |
| Contract works issue | Theft of stone and damage to part-built structures | Living plants, which many policies limit or exclude |
| What insurers ask | Wall heights, design responsibility and dig depths | Spraying certificates, tree sizes and aftercare terms |
How to compare landscapers insurance
Landscaping proposals cover design and build in one go. These points help the broker present your firm well.
Split your turnover
Give the share of design, hard landscaping, soft landscaping, public realm and street furniture work.
Explain design responsibility
Say what you design, who checks structural details and whether you use outside engineers.
Describe structures and depths
State maximum wall heights, decking heights, dig depths and any water features or garden buildings.
Schedule plant, tools and stock
List owned plant, annual hire spend, tools and nursery stock, with overnight security arrangements.
Send contract terms
Share insurance clauses from housebuilder, council and main contractor contracts, including required limits.
Quotes for landscaping firms
Tell us about your schemes, crews and design work, and a broker who arranges landscaping risks will compare cover.
Compare coverLandscapers insurance FAQs
How much does landscapers insurance cost?
Price depends on how much you design, your split between hard and soft work, the structures you build, any public realm or street furniture work, plant and tool values and your claims record. A design and build firm putting in retaining walls is rated quite differently from a planting specialist.
Does landscapers insurance cover hard landscaping?
Yes. Paving, walling, steps, decking and retaining structures are core landscaping activities. Insurers ask about maximum wall heights, foundations and design responsibility, so give those details when you ask for quotes.
Is street furniture installation covered?
It can be, if declared. Fixing benches, bollards, cycle stands and planters in streets and public spaces brings the public, traffic and highway clients into the risk. Councils and main contractors often set liability limits and may ask for proof of cover.
Do landscapers need professional indemnity?
If you produce designs, planting plans, levels or structural details for clients, yes. A design that floods a garden or needs a wall rebuilt is a financial loss to the client, which public liability does not cover. Build-only firms often do not need it.
Are dead plants covered under contract works?
Usually not. Plants and turf that fail because of drought, frost or poor aftercare are a commercial risk rather than insured damage. Many contract works policies also limit cover for trees and plants, so check what happens to living material on site.
Is tree work included in landscapers insurance?
Planting trees is usually included. Felling, climbing and work at height are often excluded unless declared, as insurers rate them as tree surgery. If your crews take down or reduce trees, tell the broker so the work can be added or arranged separately.
Does the policy cover water features and ponds?
Building them is covered as landscaping work if declared. After handover, products and completed works cover may respond if someone is hurt and your work is blamed. Insurers may ask about depths and safety measures, especially where children visit.
Does landscapers insurance cover aftercare once a scheme is handed over?
Aftercare written into a landscaping contract, such as watering and replacing failed plants during the establishment period, is usually treated as part of the scheme. Recurring mowing, hedge and site upkeep contracts are rated differently, with mowers, flying stones and spraying the main risks, so declare that work and its turnover separately.
How do I get a landscapers insurance quote?
Landscape contractors can start here: the enquiry is routed to a broker who arranges cover for this trade. Your turnover split, design responsibilities, the structures you build, a plant and stock list and the contract clauses from your main clients will help them get started.
Ready to compare landscapers insurance?
Cover for the schemes you design, the structures you build and the planting you establish, placed with insurers that understand landscape contractors.