Tilers Insurance for tiling contractors
Liability, tools, van and contract works cover for tiling firms fixing wall and floor tiles, natural stone and wet rooms on commercial and residential projects. Compare through specialist brokers who arrange cover for tiling contractors with teams on several sites.
- Public liability limits that satisfy main contractors
- Employers' liability for tilers, apprentices and labour-only teams
- Wet saws, tools and tile stock covered on site and in vans
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is tilers insurance?
Tilers insurance is a package of business covers for firms that fix ceramic, porcelain and natural stone tiles. It usually combines public liability, employers' liability, tools and equipment cover and contract works, so injury to others, damage to customers' property, staff claims and loss of materials on site are insured under one arrangement.
The claims that hurt tiling firms are rarely dramatic. A shower enclosure that was not tanked properly leaks into the kitchen ceiling below, a grinder chips a client's new bath, or a pallet of imported stone is cracked before it is ever fixed. A well built policy pays for the damage your work causes, while the cost of putting the tiling itself right usually stays with you.
Insurers rate tiling contractors on the type of work, such as domestic bathrooms, commercial floors, swimming pools or external terraces, and on how many operatives you employ or subcontract, so describing the business accurately matters.
Tilers insurance at a glance
- Suits
- Wall and floor tiling contractors with operatives, vans and a store or yard
- Core covers
- Public liability, employers' liability, tools and contract works
- Compulsory part
- Employers' liability, once you take on tilers or labourers
- Typical claims
- Water damage from failed tanking, chipped fittings, slips and dust related illness
- Insurers ask about
- Wet rooms, pools, external work, natural stone and subcontractor use
- Not included
- The cost of lifting and relaying your own defective tiling
What does tilers insurance cover?
Most tiling firms build their cover from the sections below. Each one has its own limit or sum insured on the schedule, and main contractors usually ask to see several of them before you start.
Public liability
Claims from clients, visitors and neighbours when your work hurts someone or damages their property, such as water escaping through a wet room you tanked and spoiling the floor below, or a client's vanity unit cracked by a dropped box of tiles.
Read more about public liability insurance
Employers' liability
Claims from your tilers and labourers for injury or illness, including knee damage from years of floor work and lung disease linked to dry cutting stone and porcelain. Labour-only subcontractors are usually counted as employees.
Read more about employers' liability cover
Tools and equipment
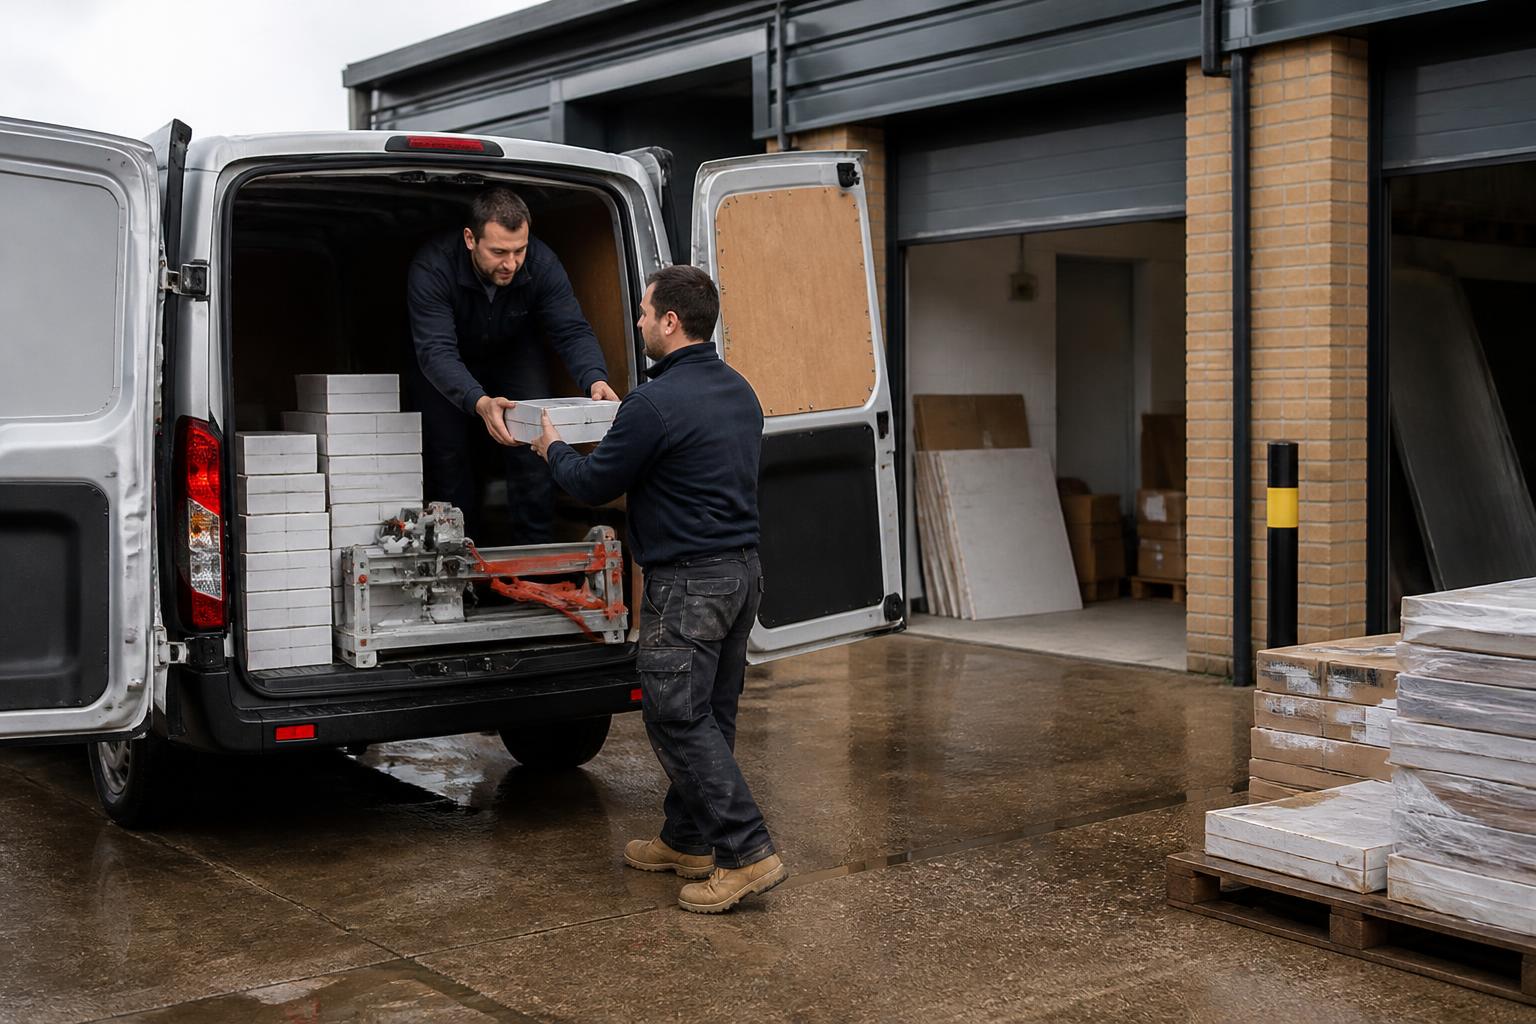
Wet saws, rail cutters, levelling systems, paddle mixers and laser levels, on site, in vans and in your store. Many insurers apply a security condition to tools left in vans overnight.
Read more about business equipment insurance
Contract works
Tiling in progress and materials delivered to site until handover. It responds if finished tiling is damaged by another trade, a burst pipe or vandalism before the client takes it over.
Read more about contractors' all risks cover
Client materials in your care
Marble, limestone and large format porcelain bought by the client can be insured while you hold them, a gap that many standard liability policies leave open.
Products and completed works
Claims after you have left site, for example a fall on a floor you laid or water damage from grout and silicone that failed months later. Most tradesman liability policies include it.
Read more about products liability insurance
Vans
The vans that carry your teams, adhesives and tile stock. Once you run several, one policy with a single renewal date is usually simpler to manage.
Read more about commercial fleet insurance
Business interruption
Lost profit if a fire or flood at your store or showroom stops you trading, which matters most for tiling firms that also sell tiles over a trade counter.
Read more about business interruption cover
Extra covers tiling firms often add
- Commercial legal expenses: chasing unpaid retentions and defending disputes over tiling a client says is uneven or out of line
- Professional indemnity: where you choose the waterproofing system, adhesive or substrate rather than following someone else's specification
- Group personal accident: income for operatives who are off work after an injury, alongside your sick pay
- Showroom and store cover: buildings, tile stock and display boards at your trade counter or showroom
Which tiling firms is this cover for?
Tiling covers a wide range of work, and insurers price each type differently. These are the firms that arrange tilers insurance with us most often.
Doing more than tiling? Firms that also plaster, fit kitchens or run wider refurbishments may be better placed under construction and tradesman insurance or another of our trade insurance guides.
- Commercial tiling contractors: floors and walls in offices, shops, hospitals and schools, usually working under a main contractor
- New-build housing tilers: kitchens and bathrooms plot by plot for housebuilders, with high volumes and tight programmes
- Bathroom and wet room installers: tanking, tiling and shower fitting, where escape of water is the claim insurers worry about most
- Natural stone and marble fixers: high value stone in hotels and private houses, much of it supplied by the client
- Swimming pool and spa tilers: submerged tiling and mosaic work, which many insurers treat as a specialist risk
- External and terrace tilers: porcelain paving, balconies and external wall tiling, sometimes from scaffold or access platforms
- Tile retailers with fitting teams: a showroom selling tiles with its own fitters, needing shop cover and contractor liability together
- Mixed flooring and tiling firms: contractors that lay vinyl, carpet and timber as well as tiles
- Plastering and tiling firms: teams that board, skim and tile as one package of work
- Builders with in-house tilers: general builders whose own staff tile as part of wider projects
How much does tilers insurance cost?
Prices are set firm by firm. These factors explain most of the difference between two tiling contractors of a similar size.
Type of tiling work
Wet rooms, pools and external work carry more risk than kitchen splashbacks and dry wall tiling, so insurers want the split of turnover across them.
Wage roll and subcontractors
Employers' liability is rated on wages, including labour-only tilers. Subcontractors who carry their own insurance are usually rated more lightly.
Turnover and contract size
Public liability is often rated on turnover, and the value of your largest job shapes the contract works sum insured.
Liability limit
Housebuilders and main contractors often set the limit you need. A higher limit costs more, but one that is too low can stop you tendering.
Tools and stock
The value of tools and stock in vans, on site and in stores, and how each is secured overnight.
Claims experience
Insurers look hard at past water damage claims and what has changed since, such as switching to a tested tanking system.
What tilers insurance usually excludes
Tiling claims are most often reduced or refused for the reasons below. Each insurer differs, so they are worth checking with the broker.
- The cost of lifting and relaying tiling that was badly fixed, as opposed to the damage it goes on to cause
- Damage to the part of the property you are working on, unless the policy has been extended to include it
- Theft of tools from a van overnight where the security condition was not met
- Pool, facade or work at height that was not declared to the insurer
- Penalties and liquidated damages for finishing late
- Design or specification errors, unless professional indemnity cover is in place
- Vans on the road, which need commercial vehicle insurance
Tilers insurance package or public liability alone?
Many tiling firms start with a single liability policy and outgrow it as they take on staff and bigger contracts. This is how the two compare.
| Feature | Tilers package | Public liability only |
|---|---|---|
| Injury to your own tilers | Covered under employers' liability | Not covered |
| Tiling damaged before handover | Covered under contract works | Not covered |
| Client stone in your care | Can be added as an extension | Often excluded |
| Wet saws and tools | Covered on site and in vans, subject to conditions | Not covered |
| Main contractor requirements | Usually meets the insurance clause in a subcontract | Often falls short of what subcontracts ask for |
How to get the right tilers insurance
A clear picture of your business helps the broker find insurers comfortable with your type of tiling.
Break down your work
Split turnover between domestic and commercial, and show how much involves wet rooms, pools, external areas or natural stone.
List your people
Directly employed tilers, apprentices, labour-only teams and subcontractors, with wages or payments for each group.
Read your subcontracts
Pull the insurance clauses from your main contracts so limits and any joint names requirements are matched from the start.
Value tools and materials
Total the tools in each van and in store, and the typical value of client materials you hold before fixing.
Explain past claims
Give details of any water damage or injury claims and what you changed afterwards.
Running a tiling firm?
Share the tiling you do, from wet rooms to stone, and your team size, and a broker used to tiling firms will line up terms.
Get a quoteTilers insurance FAQs
How much does tilers insurance cost?
It depends on the type of tiling you do, your wage roll, turnover, liability limit, tool values and claims history. A firm tiling wet rooms and pools will usually pay more than one fixing kitchen walls, and a broker can point to the parts of your work that weigh most.
Does tilers insurance cover a leaking shower we tiled?
Usually the damage the leak causes is covered, such as ceilings, floors and contents below. The cost of stripping out and redoing your own tanking and tiling usually is not, because insurers treat that as faulty workmanship. Ask the broker how the policy handles each part.
Are we covered if tiles crack or come loose after handover?
Completed works cover responds to injury or property damage the failure causes, such as someone tripping on a lifted tile. It does not pay to replace the tiles themselves. Records of substrate checks and adhesive coverage help show whether your work or building movement was to blame.
Do we need employers' liability for labour-only tilers?
Usually, yes. Insurers generally treat labour-only subcontractors as employees because you direct their work and often supply the materials. Most businesses with employees must hold employers' liability insurance, so include their payments in the wage roll you declare.
Is stone or porcelain supplied by the client covered?
Not automatically. Many liability policies exclude property in your care, custody or control. If clients supply expensive marble, limestone or porcelain, ask for an extension or a contract works section that includes it, so breakage before fixing is insured.
Are silica dust claims from staff covered?
Employers' liability covers illness claims from staff, including lung disease linked to cutting stone and porcelain. Insurers will ask about wet cutting, on-tool extraction, respiratory protection and health checks, and good controls make the risk easier to place.
What public liability limit do tiling contractors need?
Whatever your contracts ask for. Housebuilders and main contractors usually set a minimum in the subcontract, and commercial clients often want more than domestic customers. A broker will match the limit to your largest contracts rather than defaulting to the top figure.
Are our tools covered in the vans overnight?
Often only if the van meets the policy's security conditions, such as approved locks, an alarm or parking in a locked building. Some insurers exclude overnight theft from vans altogether. Check the condition and the limit per van before relying on it.
How do I get a tilers insurance quote?
Fill in the short form linked from this page, and a broker who places tiling risks follows up by phone or email. Your split of tiling work, staff and subcontractor numbers, turnover, wage roll, tool values and claims history are the details they will ask for first.
Compare tilers insurance for your firm
Liability, tools, vans and contract works for tiling contractors, arranged by a broker who understands wet rooms, stone and site contracts.