House Builders Insurance for new home builders
House builders insurance for firms building new homes on their own sites, from a handful of plots to phased estates with show homes and a sales team. Compare cover for the homes going up, the people on site and the plant, cabins and materials that keep the build moving.
- Plot-by-plot works cover from slab to handover
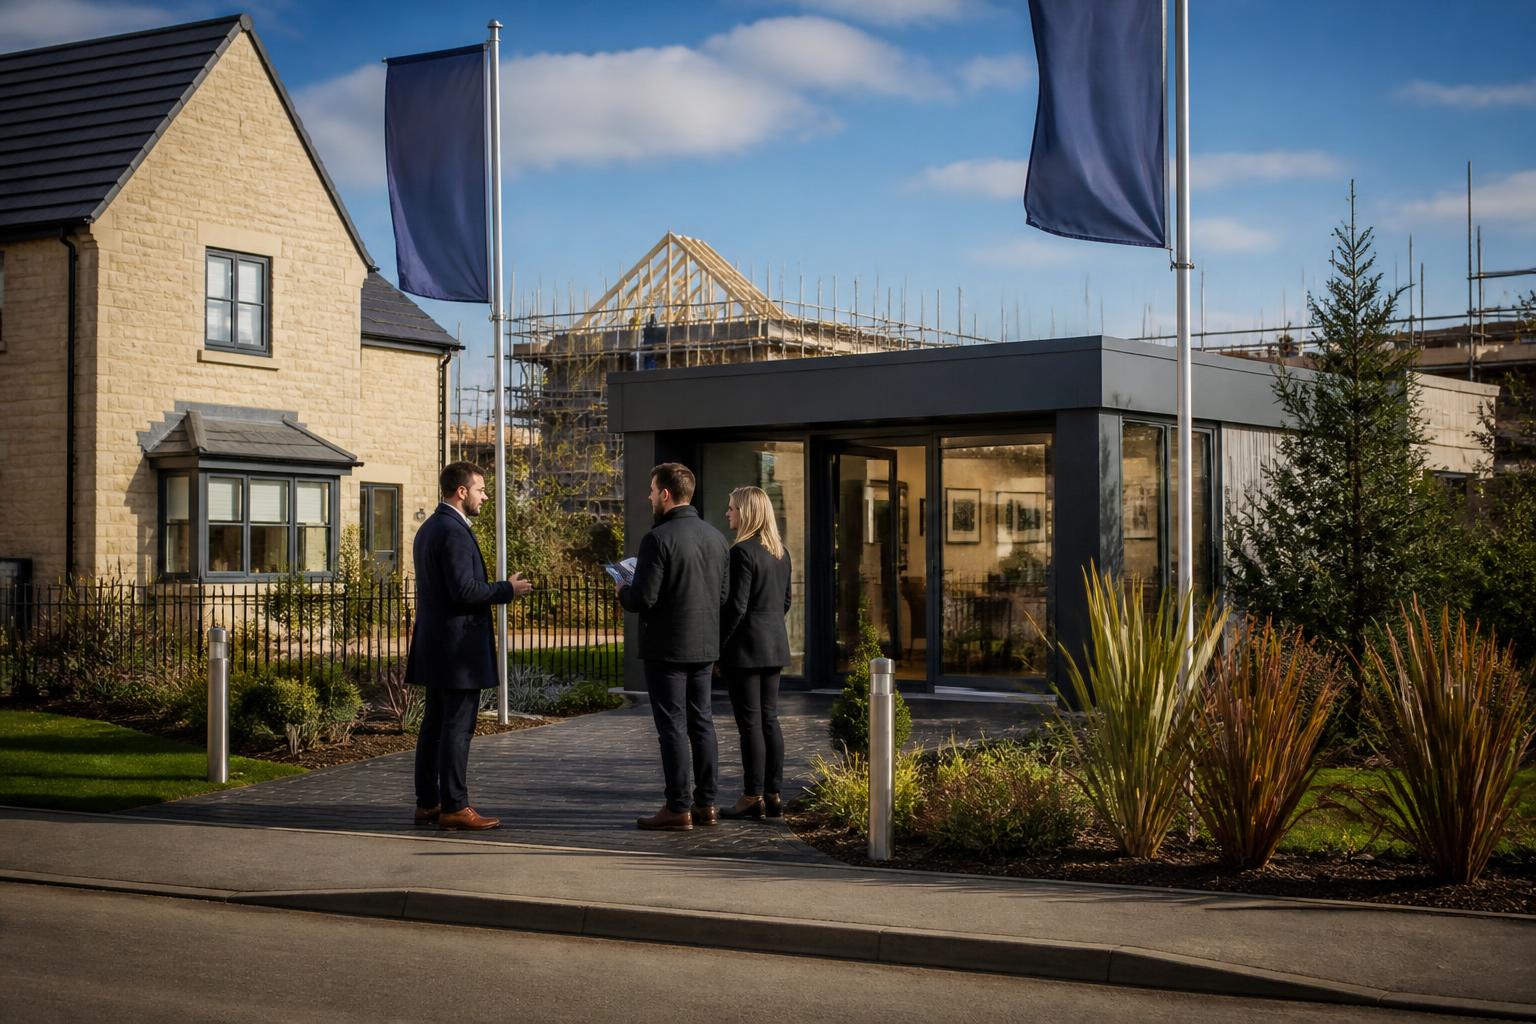
- Show homes, sales suites and visitors on a live site
- Liability for subcontractors, staff and residents of earlier phases
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is house builders insurance?
House builders insurance is a package for firms that build new homes, covering the plots under construction, the site and the people on it. It usually combines contract works, public and employers' liability, plant and site huts, and cover for show homes and sales areas until each home is handed to its buyer.
It works alongside, not instead of, the structural warranty that most lenders require on a new home. The warranty protects the buyer against defects after completion; your policy protects the business while the homes are being built and sold.
This page covers the building side of the business. Where your company also buys land and funds schemes, the ownership risks are set out on our property developers insurance page.
House builders insurance at a glance
- Suits
- Regional and local firms building homes on their own sites with staff and subcontractors
- Core covers
- Contract works by plot, public liability, employers' liability, plant and site huts
- Compulsory part
- Employers' liability, for site staff, office staff and labour-only trades
- Site extras
- Show home contents, sales suites, completed plots awaiting legal completion
- Priced on
- Annual build value, plot numbers, construction method, wage roll and security
- Separate from
- The structural warranty on each home, which is arranged with a warranty provider
What does house builders insurance cover?
Most housebuilding policies are set up on an annual basis, covering every site you start during the year up to an agreed build value. These are the usual sections.
Plots under construction
Each home from foundations to handover, plus materials on site, against fire, storm, flood, theft and vandalism, with debris removal and professional fees after a loss.
Read more about contractors' all risks insurance
Site public liability
Injury to visitors, buyers and neighbours, and damage to their property, including children trespassing onto a site at weekends.
Read more about public liability insurance
Employers' liability
Site managers, labourers, office staff and labour-only trades injured or made ill through work on your sites.
Read more about employers' liability insurance
Show homes and sales suites
Furniture, fittings and marketing displays in show homes and sales cabins, plus liability for prospective buyers walking through a live site.
Completed plots awaiting sale
Finished homes that have not yet reached legal completion, often for a limited period set in the policy, with conditions on security and inspections.
Plant, cabins and welfare units
Owned and hired-in telehandlers, dumpers and excavators, along with site offices, welfare cabins and stores.
Read more about plant and machinery insurance
Non-negligent liability
Damage to neighbouring property from subsidence or collapse caused by the works where nobody was negligent, often required for sites next to existing homes.
Pollution on site
Sudden pollution incidents, such as a fuel spill reaching a watercourse, and in some cases contamination found during groundworks.
Read more about environmental liability cover
Other cover house builders arrange
- Professional indemnity: errors by your own technical team in house types, drainage or foundations
- Commercial combined insurance: offices, IT and the yard that supports your sites
- Fleet insurance: site managers' cars, vans and tippers on one policy
- Directors' and officers' insurance: claims against the board from lenders, investors or buyers
- Legal expenses cover: disputes with subcontractors, suppliers and employees
Which firms is house builders insurance for?
It suits established firms whose main business is building new homes. These are the housebuilding firms that typically buy it.
Contracting for other clients? If most of your work is building for clients under contract, see construction company insurance, or builders insurance for extensions and smaller projects.
- Regional house builders: several sites running at once, each with a site manager, compound and show home
- Small and medium house builders: a few sites a year, usually with one site manager covering each scheme from groundworks to handover
- Builders of individual and bespoke homes: one-off and small groups of high specification homes on infill plots
- Timber frame and modular house builders: faster builds with higher fire risk while the frame is exposed, often with factory work too
- Affordable housing contractors: homes for housing associations and councils, often on phased sites next to occupied homes
- Self-build package and plot companies: firms that build homes or shells on plots for individual buyers
- Conversion builders creating new homes: turning offices, barns and listed buildings into dwellings, where existing structures need cover too
- House builders running their own groundworks: taking on excavation and drainage that would otherwise go to groundwork contractors
How much does house builders insurance cost?
Most policies are priced on the value of homes you expect to build in the year, then adjusted for the way you build and manage sites. These factors move the premium most.
Annual build value
The total value of construction you expect to carry out drives the works section, and the largest single site value sets the limit you need.
Construction method
Traditional masonry, timber frame, steel frame and modular each carry a different fire and damage risk, so insurers rate them differently.
Site security
Fencing, lighting, CCTV, alarms on show homes and how materials are stored all affect the theft and vandalism rating.
Wage roll and subcontract spend
Employers' liability is priced on direct labour, and insurers look at how many trades are labour-only rather than bona fide subcontractors.
Site surroundings
Sites close to existing homes, watercourses or rail lines, or on made ground, bring extra liability questions.
Claims and site standards
A record of theft, fire or injury claims counts, as do your site inspections, housekeeping and fire safety on timber frame plots.
What house builders insurance does not cover
These exclusions catch house builders out most often.
- The cost of correcting a defect in design, materials or workmanship itself, even where the damage it causes elsewhere is covered
- Defects found by buyers after legal completion, which fall to you and the structural warranty rather than the works policy
- Theft from unlocked plots, open containers or show homes where the security conditions were not met
- Timber frame fires where the policy's fire safety conditions for frames under construction were not followed
- Land and buildings held for future development, which belong under property developers cover
- Contractual penalties for late completion, or buyers' costs from delayed moving dates
- Site vans, tippers and cars on public roads, which go on a commercial vehicle policy or fleet cover
New home warranty or house builders insurance: which pays?
House builders need both, and buyers often confuse them. This is how responsibility usually divides between the structural warranty and your own insurance.
| Feature | New home warranty | House builders insurance |
|---|---|---|
| Who it protects | The buyer and their lender | Your firm |
| When it applies | After legal completion, for the length of the warranty | While homes are built, marketed and sold |
| Typical claims | Structural defects found in a finished home | Fire, theft, storm, site injuries and damage to neighbours |
| Defects in the early years | The builder is usually expected to fix them first | Not covered; the cost of remedying defects is excluded |
| How it is arranged | Registered plot by plot with a warranty provider, with stage inspections | An annual policy through a broker covering all sites |
How to compare house builders insurance
Housebuilding insurers want a clear picture of your programme. Have this ready before asking for terms.
Map out your programme
List current and planned sites, plot numbers, expected start dates and the largest value on any one site.
Describe how you build
Give the construction methods you use and whether any frames, pods or modules are made off site.
Separate your labour
Split direct employees, labour-only trades and bona fide subcontractors, with the annual spend on each.
Show your site controls
Explain security, show home alarms, fire safety on frames, inspections and how materials are stored.
Bring your claims record
Note any theft, fire, injury or neighbour claims, and what your site procedures changed afterwards.
Quotes for house builders
Share your sites, build programme and plot values, and a broker who arranges housebuilding cover will compare options.
Compare quotesHouse builders insurance FAQs
How much does house builders insurance cost?
It is priced mainly on the value of homes you plan to build in the year, then adjusted for construction method, site security, labour, surroundings and claims history. Timber frame builders and firms on tight urban sites are usually rated differently from traditional builders on open land.
Do I need a structural warranty as well as insurance?
Usually, yes. Most mortgage lenders will not lend on a new home without a structural warranty from a recognised provider, though some accept a professional consultant's certificate on smaller schemes. Plots generally have to be registered before work starts. Your house builders policy is separate and protects the business during the build.
Does the policy cover show homes?
It can. Show home and sales suite contents can be added, along with liability for visitors. Insurers usually expect show homes to be alarmed and locked when unattended, and may ask how visitors are kept away from live construction areas.
Are completed homes covered before the buyer moves in?
Many policies cover finished plots until legal completion, though often only for a limited period after practical completion and with security conditions. Homes left unsold for longer may need separate cover, so check the period with your broker.
Can one policy cover all my sites?
Yes. Most house builders buy an annual policy that covers every site started in the year, up to a declared build value and a maximum value for any single site. Larger or unusual schemes may need to be referred to the insurer before work begins.
Does house builders insurance cover my subcontractors?
Labour-only trades are usually treated as your employees and fall under your employers' liability. Bona fide subcontractors need their own liability policies, and many insurers make checking those policies before work starts a condition of cover.
Is residents' property covered on a phased site?
Damage to residents' property and injury to residents caused by your works are normally covered by public liability. Expect the underwriter to ask how occupied phases are kept apart from live construction, including fencing, traffic routes and deliveries.
What if a timber frame catches fire during construction?
Fire damage to the works is covered under the contract works section, provided you met the policy's fire safety conditions. Insurers often set specific requirements for timber frame sites, such as security, storage of materials and controls on hot work.
How do I get a house builders insurance quote?
Outline your housebuilding programme in the enquiry form here. A broker who arranges cover for house builders will then ask for site details, build values, construction methods and claims history, and present the options insurers offer.
Ready to compare house builders insurance?
Cover for every plot, show home and site you run, arranged by a broker who understands housebuilding programmes.