Skip Hire Insurance for skip and waste firms
Skip hire insurance for operators running skip loaders, hook lift lorries and a waste yard or transfer station. Compare fleet, liability and site cover through brokers who understand waste fires, skips on the highway and loading accidents.
- Fleet cover for skip loaders and hook lift lorries
- Liability for skips on roads and customers' driveways
- Yard, plant and fire cover for waste sites
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is skip hire insurance?
Skip hire insurance is a combination of covers for firms that deliver, collect and empty skips. It usually brings together motor insurance for skip loaders and hook lift lorries, public liability for skips left on roads and private land, employers' liability for drivers and yard staff, and cover for skips, plant and the yard itself.
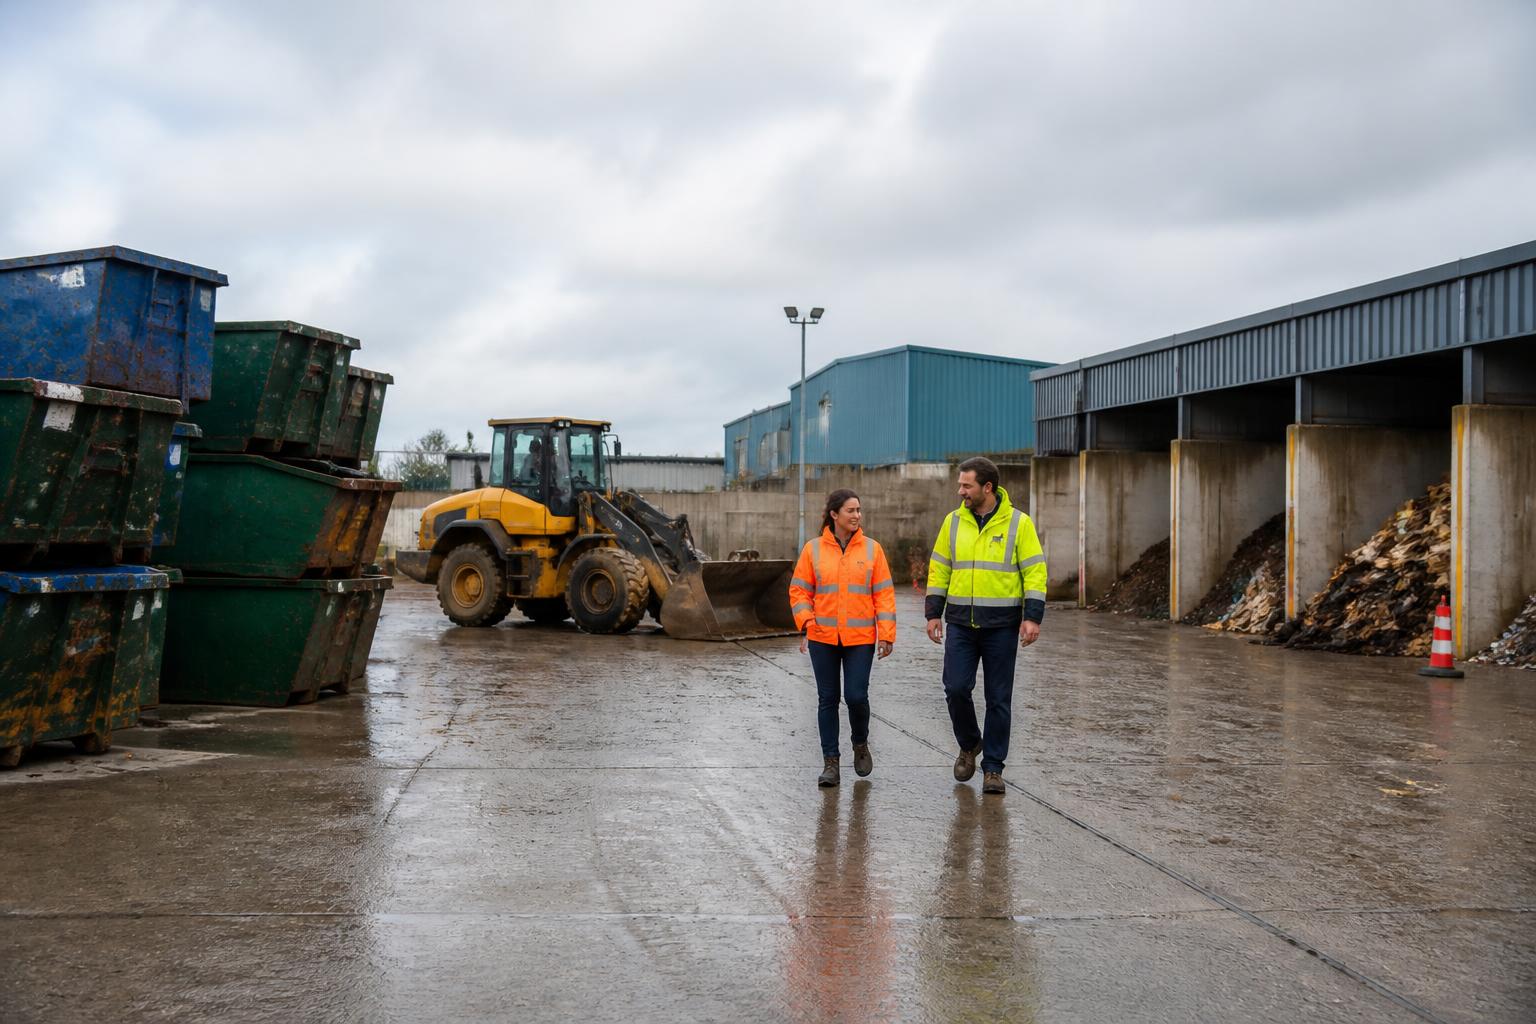
The risk changes sharply once you run a waste transfer station. Stored waste is one of the harder fire risks for insurers to place, and sorting lines, balers and loading shovels add plant and injury exposure. Insurers ask about stockpile sizes, fire breaks, detection and the types of waste you accept.
Skip hire insurance at a glance
- Suits
- Skip hire operators, waste carriers and transfer station operators
- Starting point
- Motor fleet, public liability and employers' liability
- Site covers
- Buildings, plant, skips and containers, business interruption
- Often added
- Environmental liability, goods in transit, legal expenses
- Priced on
- Fleet size and drivers, waste types, yard fire controls, turnover, claims
- Hardest part
- Fire cover for stored waste at transfer stations
What does skip hire insurance cover?
Skip firms usually combine a fleet policy with a combined policy for the yard. Between them they hold the sections that make up the package.
Skip loaders and hook lifts
Motor cover for your lorries on the road, with drivers named or covered by age and experience, and cover for the vehicle while lifting or tipping where the insurer agrees.
Read more about fleet insurance
Skips on the road
Injury and damage when a vehicle or cyclist hits a skip placed on the highway, including claims that lighting or markings had failed.
Read more about public liability insurance
Damage at customers' premises
Cracked driveways and block paving, damaged walls and gates, and overhead cables caught while placing or lifting skips.
Employers' liability
Injury to drivers, yard operatives and pickers, including crush injuries from skips and chains, manual handling on picking lines and contact with sharps or hazardous waste.
Read more about employers' liability insurance
Skips and containers
Your stock of skips, roll-on roll-off containers and compactors, on hire and in the yard, against fire, theft and malicious damage.
Yard plant
Loading shovels, excavators with grabs, telehandlers, trommels, balers and shredders, against damage, theft and breakdown.
Read more about plant and machinery insurance
Yard and transfer station
Buildings, sorting sheds and equipment at your site against fire and other damage. Insurers look closely at fire detection, stockpile limits and separation.
Read more about commercial property cover
Business interruption
Income lost while a burnt-out site is rebuilt, with extra costs such as gate fees for tipping at someone else's transfer station.
Read more about business interruption insurance
Pollution and clean-up
Sudden escapes of fuel, oil, leachate or contaminated firewater from your site or vehicles. Cleaning up your own land usually needs an environmental policy.
Read more about environmental liability insurance
Other covers skip and waste firms add
- Engineering inspection: periodic examination of skip lifting gear, hook lifts and plant
- Goods in transit: recyclables and baled materials you sell and deliver
- Commercial legal expenses: disputes over permits, contracts and motor claims
- Directors' and officers' cover: defence costs if directors are pursued personally after a serious incident or pollution event
Which firms need skip hire insurance?
It suits any established business moving waste in skips or containers. Typical operators are listed below.
Running heavier haulage too? See HGV and haulage insurance, or browse the trades hub.
- Skip hire operators without a site: a fleet of skip loaders tipping at other firms' transfer stations, where motor and highway liability are the main risks
- Skip hire with a transfer station: sorting and storing waste on your own site, which brings fire, plant and pollution cover into the package
- Roll-on roll-off container firms: hook lift lorries and large containers serving construction sites, factories and retail parks
- Commercial waste collectors: trade waste bins, compactors and balers alongside skips, with a larger collection fleet
- Grab hire firms: grab lorries removing muck and aggregates from sites, often working with groundwork contractors
- Recycling and materials recovery operators: sorting lines, picking stations and baled output sold on, with products and transit exposure
- Demolition and clearance contractors with skips: firms supplying their own skips to their sites, often alongside building contracts
How much does skip hire insurance cost?
Skip hire pricing splits between the fleet and the yard. Insurers look at each half separately.
Fleet size and drivers
The number of lorries, their value, the drivers' ages and experience and your motor claims history drive the largest part of most premiums.
Vehicle safety and telematics
Cameras, sensors for vulnerable road users, telematics and driver training can all count in your favour.
Transfer station or not
Operating a site with stored waste changes the risk substantially, and some insurers will only write the fleet.
Waste types accepted
Insurers ask about wood, plastics, tyres, batteries and hazardous waste, and how you quarantine loads that arrive with them.
Fire controls on site
Stockpile sizes, separation distances, fire detection, water supply, thermal monitoring and out-of-hours security are all assessed.
Yard staff and picking lines
Manual sorting brings sharps, crush and handling injuries, so the number of pickers and how lines are guarded weigh on employers' liability.
What skip hire insurance will not pay for
Skip firms most often find a claim reduced or refused for one of these reasons.
- Skips placed on the road without a permit, or without the lighting and markings the permit requires
- Fire at a waste site where the agreed stockpile limits or fire conditions were not followed
- Gradual pollution and long-term contamination of your site, unless environmental cover is in place
- Hazardous waste you are not permitted to handle
- Damage to driveways where the customer chose the position against your driver's advice, depending on the policy and your hire terms
- Wear and tear to skips and containers, such as corrosion and worn floors
- Theft of skips from customers' premises, unless the policy extends to skips on hire
Skip hire only or skip hire with a waste site?
The insurance needs of a skip hire firm change most when it opens its own transfer station. This is how the two set-ups compare.
| Feature | Skip hire only | Skip hire with a waste site |
|---|---|---|
| Main risk | Motor accidents and skips on the highway | Fire in stored waste, plus everything on the left |
| Policies needed | Fleet policy and a liability policy | Fleet, combined site policy, plant and pollution cover |
| Insurer appetite | Many motor and liability insurers will quote | A narrower group writes waste site property |
| Survey | Rarely needed | Usually required before terms are confirmed |
| After a loss | Replacement lorry hire, if the motor policy includes it | Tipping elsewhere and lost profit after a fire |
How to compare skip hire insurance
Skip and waste proposals cover a fleet and a site. Brokers move faster with this in hand.
List the fleet and drivers
Vehicles with registrations and values, drivers with licence details, and your motor claims history.
Describe your site
Layout, buildings, waste types accepted, stockpile sizes, fire detection, water supply and security.
Schedule skips and plant
Number and value of skips and containers, and the plant you own or hire in.
Confirm your permits
Your waste carrier registration, site permit and the way you arrange road permits for skips.
Add trading figures
Annual turnover, gross profit and payroll, and an account of each recent claim and what you changed afterwards.
Quotes for skip and waste firms
Describe your lorries, yard and waste streams, so a waste specialist can approach insurers on your behalf.
Get a quoteSkip hire insurance FAQs
How much does skip hire insurance cost?
The fleet, your drivers and motor claims usually set the biggest share, then whether you run a transfer station, what waste you accept and how you control fire. A fleet-only operator is priced very differently from one storing waste on site.
Who is liable if someone hits one of my skips on the road?
Claims often come to the skip firm, especially if lighting or markings had failed or the conditions of the council's skip permit were not met. Public liability covers your legal liability for the injury or damage, so keep records of permits and lighting checks.
Does skip hire insurance cover damage to a customer's driveway?
Public liability can cover damage caused by your vehicles or skips at a customer's property, subject to the excess. Many firms also set out in their hire terms who is responsible for placement on private surfaces, which can affect how a claim is handled.
Is the lorry covered while it is lifting a skip?
Many motor policies cover the lorry while lifting and tipping, but some limit liability once the vehicle is working as a tool rather than being driven. It is worth asking the broker how your motor and public liability policies split this, so a lifting accident does not fall between them.
Why is fire cover for a waste transfer station hard to get?
Stored waste can self-heat and contains items such as batteries that start fires, and fires at waste sites can burn for days. Fewer insurers write it, and those that do set conditions on stockpile size, separation, detection and quarantine areas.
Do skip hire firms need environmental liability insurance?
It is worth considering if you run a site. Public liability usually covers only sudden pollution affecting others. An environmental policy can cover gradual pollution and the cost of cleaning up your own land and nearby watercourses.
Are skips on hire covered against theft and fire?
Only if the policy extends to skips away from your premises. Many operators insure their skip stock on the combined policy with cover on hire, sometimes with a limit per skip and an excess.
Can I get skip hire insurance after a site fire?
Usually, through a specialist broker, but expect questions about the cause and the changes made since. New fire detection, smaller stockpiles and better quarantine of risky waste all help.
How do I get a skip hire insurance quote?
Begin on this page. Your enquiry is passed to a broker who arranges waste and fleet cover. Helpful information includes your vehicle and driver list, site plan, accepted waste streams, permits, skip and plant values, and motor and property claims.
Ready to compare skip hire insurance?
Lorries, skips, yards and the liability that follows them, placed with insurers that write waste businesses.