Shop Fitters Insurance for fit-out contractors
Insurance for shop fitters and interior fit-out contractors working in stores, restaurants, bars, offices and showrooms across the UK. Compare cover for your joinery workshop, site teams, transport and the contract terms national clients set.
- Liability for work in trading stores and shopping centres
- Contract works for fixtures and fittings until handover
- Joinery workshop, machinery and finished units insured
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is shop fitters insurance?
Shop fitters insurance is a commercial package for contractors who make and install retail, hospitality and office interiors. It normally pairs public and products liability and employers' liability with contract works, workshop property, goods in transit and, for design and build firms, professional indemnity, so site, factory and design risks are covered together.
Fit-out work usually happens in someone else's live business. Teams work overnight in trading stores surrounded by stock, in shopping centres with strict access rules, or in restaurants that must reopen on a fixed date. Damage to a client's stock, a fire started by a cutting disc, or dust through a store's ventilation can lead to large claims, while the joinery workshop behind the business brings its own fire and machinery risks.
The same package suits office fitters and point of sale and display installers. Insurers will want to know whether you design or build to others' drawings, the size of your largest contract, how much is subcontracted and whether you work outside the UK.
Shop fitters insurance at a glance
- Suits
- Fit-out contractors with site teams, a joinery or metal workshop and national clients
- Core covers
- Public and products liability, employers' liability, contract works and workshop
- Compulsory part
- Employers' liability, for site and workshop employees
- Trade specific
- Work in trading premises, client stock, wood dust, design and build
- Contracts often ask for
- Joint names contract works, set liability limits and collateral warranties
- Usually separate
- Delivery vehicles, on a fleet policy
What does shop fitters insurance cover?
Fit-out contractors usually combine the sections below. The schedule sets the limit or sum insured for each, and some sections can be tailored to a single large contract.
Public liability
Damage to the client's building, stock and fixtures, and injury to shoppers, diners and staff while you work. Shopping centres and national retailers usually set a minimum limit before you are allowed on site.
Read more about public liability insurance
Products and completed works
Claims after the store opens, such as a shelving run collapsing, a counter top falling on a customer or a sign coming away from its fixings.
Read more about products liability cover
Employers' liability
Injuries to fitters, joiners and labourers, including machine injuries in the workshop, falls from towers and lifting heavy units, and illness from wood dust.
Read more about employers' liability insurance
Contract works
The fit-out itself while it is being built, from counters and ceilings to glazing and lighting, until handover. Many clients ask for this in joint names.
Read more about contractors' all risks insurance
Workshop and machinery
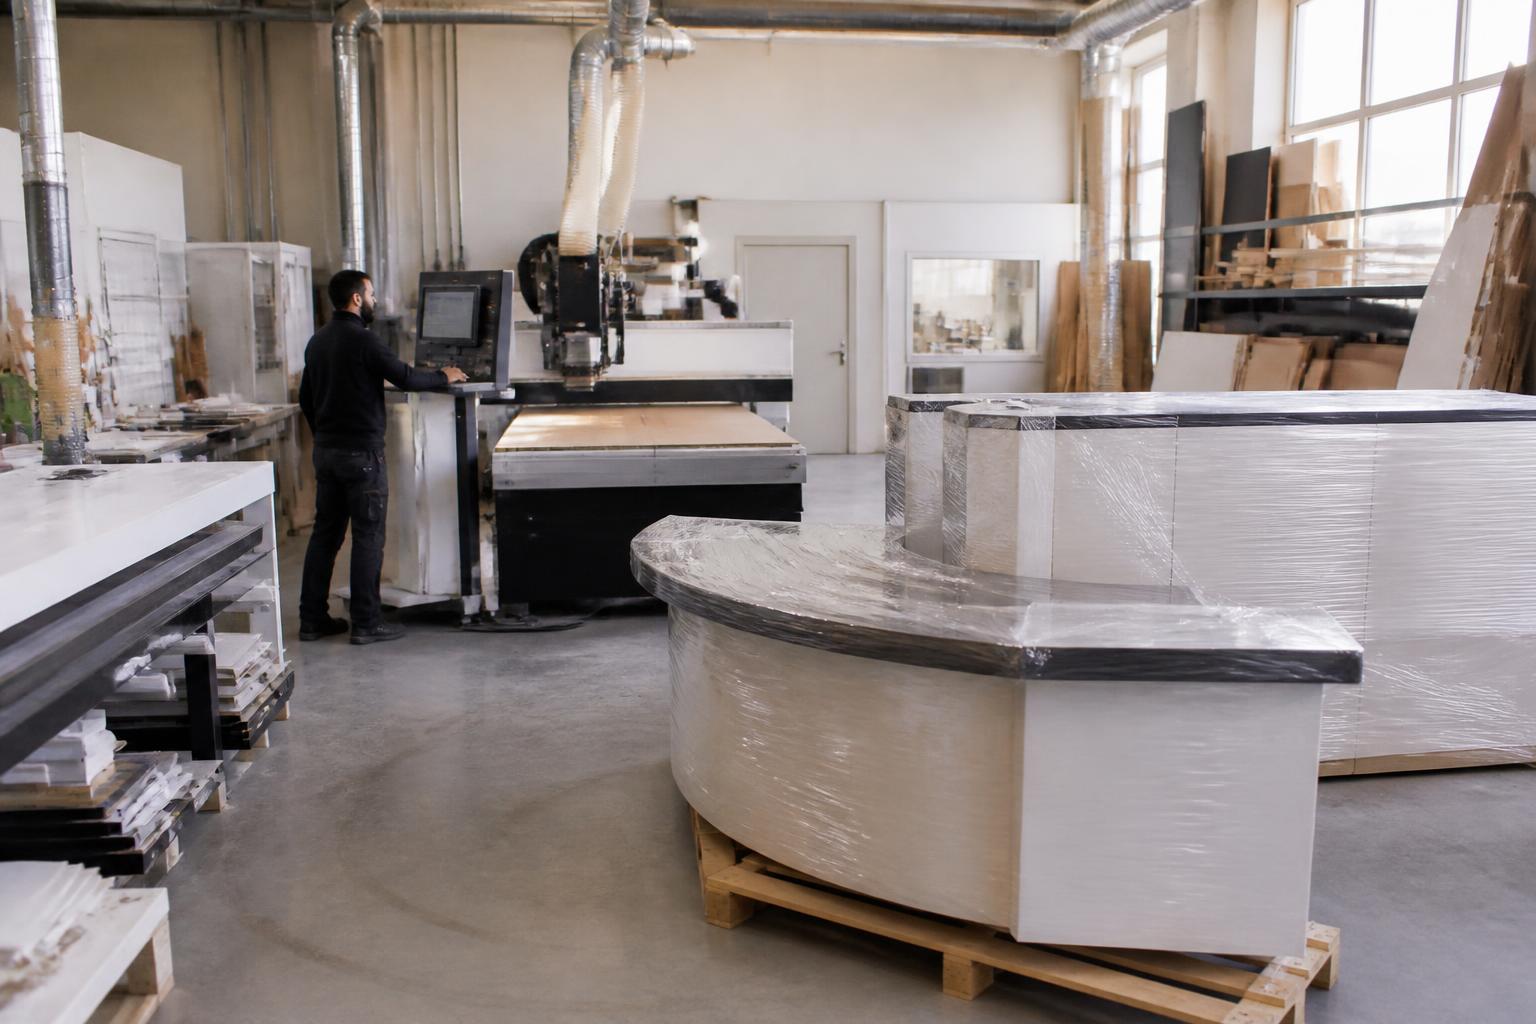
Your joinery or metal workshop, CNC routers, panel saws, edge banders, spray booths and finished units waiting to go out.
Read more about business equipment and machinery insurance
Goods in transit
Finished displays, counters and fixtures carried from your workshop to stores across the country, in your own lorries or with hauliers.
Read more about goods in transit insurance
Professional indemnity
Claims that your design, layout or specification was wrong, such as a bar layout that fails a fire check or a display system that cannot carry the stock it was designed for.
Read more about professional indemnity insurance
Business interruption
Income lost when a workshop fire or a machine breakdown halts production, leaving you unable to meet programmes for opening dates.
Read more about business interruption cover
Other cover fit-out firms often need
- Group personal accident and travel: for teams working away from home on national roll-outs and projects abroad
- Trade credit insurance: protection against a retail or hospitality client failing mid-project
- Commercial legal expenses: adjudication and payment disputes with main contractors and clients
- Engineering inspection: examinations of dust extraction, spray booths and lifting equipment in the workshop
Which fit-out businesses is this for?
Shop fitting covers many building types and contract models. These are the firms we see arranging shop fitters insurance most often.
Wider building work? Contractors taking on structural alterations alongside fit-out can see construction company insurance or other trade insurance guides.
- Retail shop fitters: store fit-outs and refits for national chains and independent retail businesses, often overnight in trading stores
- Hospitality fit-out contractors: bars, coffee shops and other hotels, pubs and restaurants, where opening dates are fixed and back of house areas are complex
- Office fitters and fit-out contractors: partitions, ceilings, joinery and furniture installation for office-based businesses and their landlords
- Joinery and display manufacturers: workshops making counters, shelving, fixtures and point of sale displays, with or without installation
- Point of sale and display installers: fitting branded displays, gondolas, signage units and promotional fixtures in stores and shopping centres, often overnight and across many sites in a short campaign
- Design and build fit-out firms: taking responsibility for layout and specification as well as delivery
- Roll-out and maintenance contractors: repeat refits and planned maintenance across a client's store estate
- Exhibition and showroom builders: stands, car showrooms and brand spaces built and dismantled to tight timescales
- Fit-out firms with flooring teams: contractors laying floors as part of their package
- Shopfront specialists: fitting glazed shopfronts and entrances as part of a store fit-out
How much does shop fitters insurance cost?
Insurers price each fit-out firm on its contracts, workshop and design role. These factors move the premium most.
Design responsibility
Firms that design as well as build need professional indemnity and face larger claims, so the split of design and build work matters.
Contract values
Your biggest fit-out and your total contract turnover for the year decide the contract works sum insured and feed into the liability rating.
Workshop risk
Wood dust, spray finishing and machinery bring fire risk, and insurers look at extraction, housekeeping and fire protection.
Where you work
Trading stores, shopping centres, airports and hotels raise the potential size of a claim, as can work abroad.
Labour and subcontractors
Employers' liability follows the wage roll, including labour-only fitters, and insurers check that subcontractors carry their own cover.
Claims history
Damage to client stock and premises, workshop fires and injury claims are reviewed alongside the steps taken since.
What shop fitters insurance typically excludes
These are the exclusions that matter most on fit-out contracts. Read them against your current contract terms.
- Liquidated damages for missing an opening date, which are a contract risk rather than an insured one
- The cost of remaking joinery or fittings that were made or installed wrongly
- Design errors, unless a professional indemnity section has been arranged
- Fire caused by hot work where the policy's permit and fire check conditions were not met
- Work outside the UK, unless the territorial limits have been extended
- Loss of the client's trading income on its own, where nothing has been physically damaged
- Lorries and vans on the road, which need commercial vehicle insurance
Building to drawings or design and build?
The biggest change to a fit-out firm's cover comes when it takes on design responsibility. This is how the two models compare.
| Feature | Build to client's design | Design and build |
|---|---|---|
| Professional indemnity | Often not needed, unless you design elements such as joinery details | Normally required by the contract |
| Collateral warranties | Sometimes requested | Commonly requested by landlords and funders |
| Who answers for a layout error | Usually the designer | Your firm |
| Contract works | Often in joint names with the client | Usually arranged by you for the whole project |
| Typical clients | Main contractors and architects | Retailers, operators and developers directly |
How to compare shop fitters insurance
A full picture of your contracts and workshop helps the broker approach insurers that write fit-out risks.
Describe your contracts
List your largest and typical contract values, clients and sectors, and how many involve design.
Outline the workshop
Building, machinery, dust extraction, spray finishing, fire protection and stock values.
Detail your labour
Employed staff, labour-only fitters and subcontracted trades, with wages and payments.
Flag where you work
Trading stores, shopping centres, airports, overseas projects and any night work.
Pull contract insurance clauses
Joint names, limits, collateral warranties and any requirement for non-standard extensions.
Fit-out firm? Get cover compared
Tell us about your fit-out work and workshop and a specialist broker will compare cover.
Get a quoteShop fitters insurance FAQs
How much does shop fitters insurance cost?
It depends on your contract values, design role, workshop, wage roll, where you work and your claims history. A design and build firm with a large joinery shop will pay more than an install-only team. A broker can explain which sections are driving your premium.
Does public liability cover damage to a client's stock?
Generally, yes. Damage to stock and fixtures in a store you are working in is third party property damage. Some policies exclude property in your care or the part you are working on, so check how the policy treats goods you move or cover during the work.
Do we need professional indemnity as shop fitters?
If you produce layouts, specify materials or take on design and build contracts, it is usually needed. Public liability does not cover a client's financial loss from a design that does not work, and many fit-out contracts make professional indemnity a requirement.
Can contract works be arranged in joint names with the client?
Yes. Many fit-out contracts ask for contract works cover in the joint names of the contractor and employer. Insurers can note the client's interest on an annual policy, or arrange cover for a single project where the contract requires it.
Are we covered if a store misses its opening date?
Not for late completion itself. Liquidated damages and penalties for delay are usually excluded. If a fire or flood on site causes the delay, contract works pays to rebuild the damaged work, but the client's own delay costs usually remain a contract matter between you.
Is our joinery workshop covered for fire and dust risks?
A property and machinery section can cover the building, machinery and stock against fire and breakdown. Insurers will look at dust extraction, cleaning routines, waste removal and any spray booths, and may set conditions that must be followed.
Can we get cover for fit-out work abroad?
Usually, if it is declared. Many trade policies limit cover to the UK, so overseas projects need the territorial limits extending and may require local insurance. Employees travelling abroad may also need group travel and personal accident cover.
What liability limit do shopping centres and national retailers ask for?
Each sets its own minimum, often higher than smaller clients ask for. Contracts and site rules usually state the limit, whether it applies per claim, and which insurance documents you must show before starting work.
Does shop fitters insurance cover office fitters and point of sale installers?
Yes. Office fitters usually buy the same liability, contract works and workshop cover, with more focus on occupied office floors and landlord requirements. Point of sale and display installers need liability for work in trading stores and transit cover for displays carried between sites.
How do I get a shop fitters insurance quote?
Fill in the short enquiry on this page and a broker who places fit-out risks will arrange a call. Contract values, design work, workshop details, wage roll, subcontractor spend and claims history are the main things they need before approaching insurers.
Compare shop fitters insurance
Liability, contract works, workshop and design cover for fit-out contractors, arranged by a broker who understands opening dates and live stores.