Marquee Hire Insurance for marquee and structure firms
Insurance for companies that hire out and erect marquees, frame tents, stretch tents and temporary structures for weddings, corporate events, festivals and shows. Compare cover built around weather, the stock you own and the people gathered under your structures.
- Liability when a structure moves or fails in wind
- Marquees, flooring, furniture and heaters insured
- Crews staking, rigging and building on uneven ground
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is marquee hire insurance?
Marquee hire insurance is a combined policy for businesses that supply and erect marquees, tents and temporary structures. It usually includes liability to guests, the public and your own crew, cover for marquee stock, flooring, furniture and equipment both in store and out on hire, goods in transit and, often, cover for hired-in plant and vehicles.
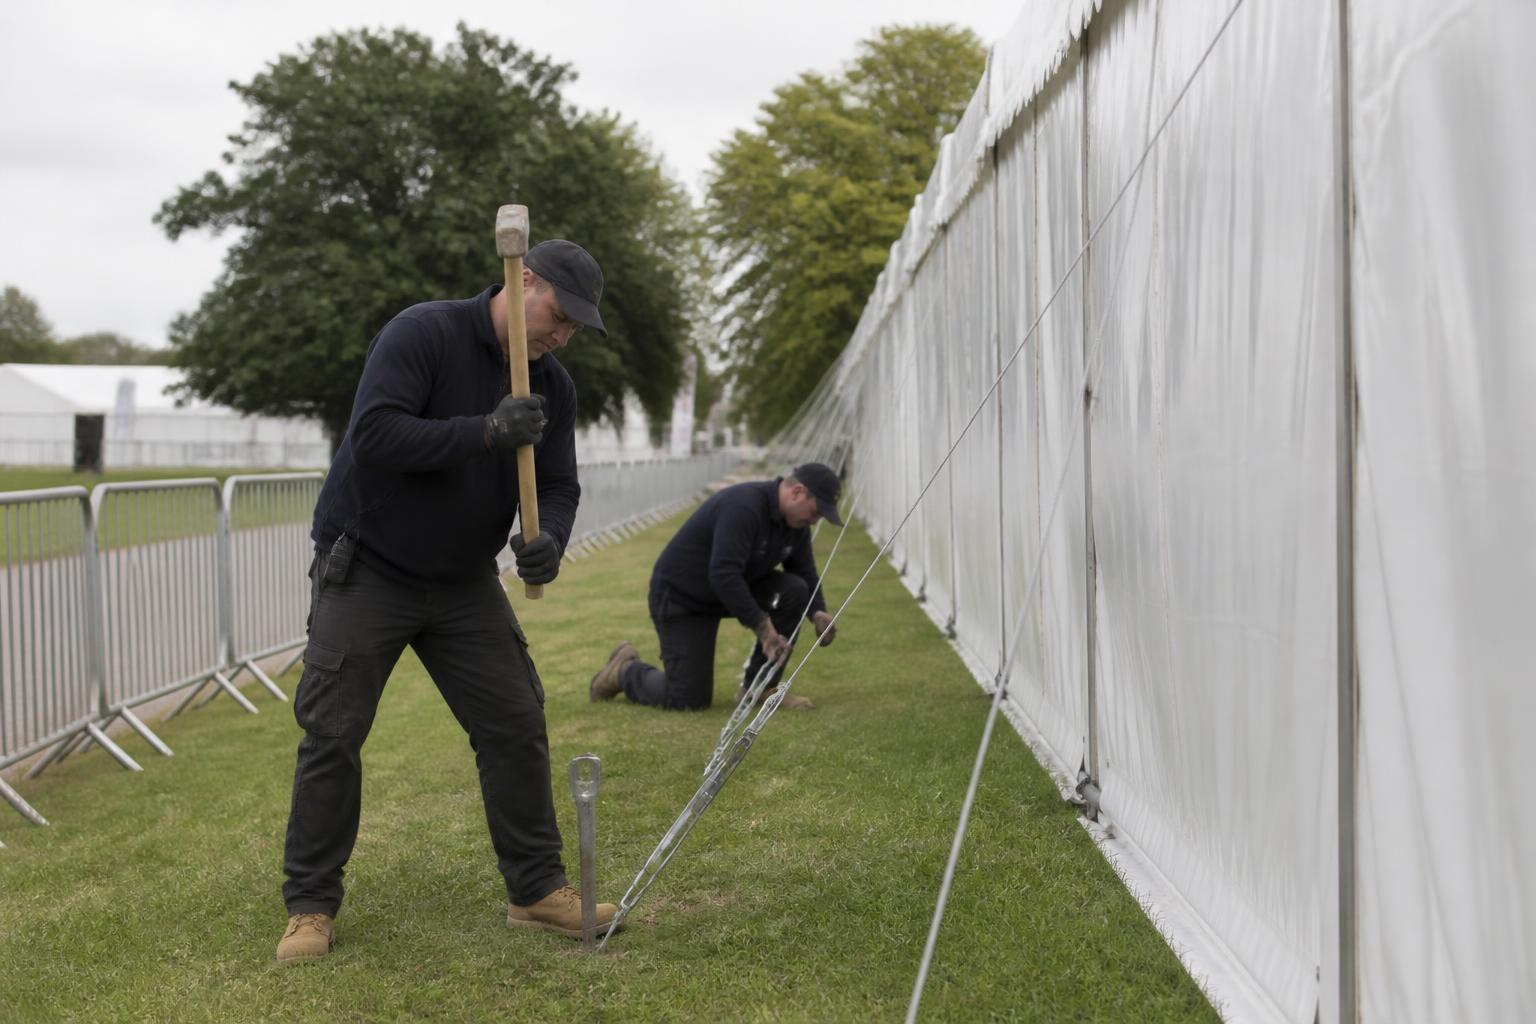
Wind is the defining risk. A structure that lifts, shifts or collapses with guests inside can cause serious injuries and very large claims, so insurers look closely at how you anchor, how you monitor the weather, and when your crew or the client must evacuate and take a structure down. Staking carries its own risk too: a pin driven into a lawn or field can hit a buried water pipe, power cable or drain.
Insurers also want to know whether you only supply equipment or erect and manage it, what heating, lighting and power you provide, and how often your stock is left on site unattended.
Marquee hire cover at a glance
- Suits
- Marquee and structure firms with stock, crews, a yard and vehicles
- Core sections
- Public and products liability, employers' liability, hire stock, transit
- Must have
- Employers' liability for crews and yard staff
- Trade specific
- Wind loading, staking into buried services, heaters, stock left on site
- Insurers look for
- Wind management plans, anchoring records and handover checks
- Covered elsewhere
- Organisers' cancellation risks, under event and contingency insurance
What does marquee hire insurance cover?
Structure firms usually combine the sections below. Stock on hire and storm conditions are the details that vary most between insurers.
Public liability
Injury to guests, staff and the public, and damage to clients' grounds, buildings and services, during erection, the event itself and take-down.
Read more about public liability insurance
Products and structure failure
Claims when a structure you erected moves, collapses or sheds a panel during an event, including after your crew has left site.
Read more about products liability cover
Employers' liability
Injury to crew driving stakes, lifting frames and roof sections, working at height on larger structures and handling heavy flooring.
Read more about employers' liability insurance
Marquee and hire stock
Canvas and PVC roofs, frames, flooring, linings, furniture, lighting and heating, covered in your yard and while out on hire.
Read more about business equipment insurance
Goods in transit
Stock carried to and from sites on your own trucks and trailers, including loading and unloading on soft ground.
Read more about goods in transit insurance
Plant, owned and hired in
Telehandlers, forklifts, stake drivers and generators, including plant hired for a large build.
Read more about plant and machinery insurance
Heaters, power and fire
Gas and electric heaters, generators and lighting supplied with structures add fire and products risk that insurers need to know about.
Yard and storage
Your yard, warehouse, wash bays and repair areas, where large stocks of fabric and furniture create a serious fire load.
Read more about commercial property insurance
Other cover marquee firms often add
- Business interruption: lost bookings if a fire at your yard destroys stock in the season
- Fleet insurance: trucks, trailers and vans on one policy
- Commercial legal expenses: deposit disputes and damage claims against hirers
- Group personal accident: benefits for crew injured during builds
Which marquee and structure businesses is this for?
We arrange cover for firms supplying temporary structures for private, corporate and public events.
Running the event yourself? If you organise the event as well as supplying the structure, cancellation cover is explained on our event and contingency insurance page, and permanent venues on our leisure and entertainment insurance page.
- Marquee hire companies: wedding, party and corporate marquees supplied, erected and dressed for clients
- Tent and marquee erection crews: building and taking down structures for hire firms and organisers on a contract basis
- Clearspan and temporary structure firms: large frame structures for shows, festivals and temporary retail
- Stretch and tipi tent suppliers: stretch tents, tipis and bell tents for weddings, festivals and glamping
- Event furniture and flooring hire firms: flooring, furniture, staging and lighting supplied with or without a structure
- Festival and show contractors: structures for festivals, county shows and sporting events, working for event organisers and show societies
- Hospitality structure suppliers: seasonal and semi-permanent structures for hotels, pubs and restaurants and wedding venues
- Temporary building hire firms: structures used as overflow storage, workshops and canopies for warehousing and industrial clients
How much does marquee hire insurance cost?
Insurers look at the size of what you put up and how you manage the weather. These factors shape the premium most.
Size of structures
Large clearspan structures holding hundreds of guests carry more liability weight than small party marquees.
Supply only or erected
Dry hire, where the client puts the equipment up, and full erection by your crew are rated differently.
Weather controls
Wind monitoring, anchoring methods and clear evacuation and take-down triggers change how insurers see the risk.
Stock values and storage
The value of fabric, frames, flooring and furniture, and fire protection at your yard, drive the property sections.
Heating and power
Supplying gas heaters, generators and lighting increases fire and products exposure.
Claims history
Storm losses, structure failures and injuries during builds are reviewed, along with what changed afterwards.
What marquee hire insurance usually excludes
These exclusions matter most to a structure hire firm, especially in the storm season.
- Storm damage to stock left standing when the policy's wind or take-down conditions were not followed
- Theft of stock left unattended on site, unless agreed with the insurer
- Damage hirers cause to equipment on dry hire, unless cover for hired-out stock is included
- Damage to buried services where no checks were made before staking
- Event cancellation, which organisers cover through event contingency insurance
- Mould, damp and gradual deterioration of stored fabric
- Heaters and generators supplied without being declared
Dry hire or erected and managed?
Many firms offer both, sometimes to the same client. The difference in who builds the structure changes where liability sits.
| Feature | Dry hire | Erected and managed |
|---|---|---|
| Who puts it up | The client or their contractor | Your own crew |
| Main liability risk | Faulty or incomplete equipment supplied | How the structure was built and anchored |
| Damage to your stock | In the hirer's hands for the hire period | Under your control, apart from guests |
| Employee exposure | Yard, loading and delivery only | Staking, lifting and building on site |
| Weather decisions | Usually left to the hirer | Often shared, as set out in your terms |
How to get marquee hire insurance quotes
Structure risks are assessed on detail, so prepare these points before speaking to the broker.
Describe your structures
Types, sizes, largest capacity and whether you supply only, erect or both.
Explain weather controls
How you anchor, monitor wind and decide when to evacuate or take a structure down.
Value your stock
Fabric, frames, flooring, furniture, heating and lighting, with yard security and fire protection.
List crew and vehicles
Employed crew, seasonal staff, trucks, trailers and plant owned or hired.
Check your hire terms
Clauses on hirer responsibility, damage deposits and weather, and the limits clients ask for.
Get marquee cover compared
Tell us about your structures, stock and crews and a broker will compare cover.
Get a quoteMarquee hire insurance FAQs
How much does marquee hire insurance cost?
It depends on the size and type of structures, whether you erect or dry hire, stock values, heating and power, your weather procedures, wage roll and claims history. Firms erecting large structures for public events usually pay more than those supplying small party marquees.
Are we covered if a marquee blows down during an event?
Injury and damage to others are usually covered under public and products liability, provided policy conditions were met. Insurers often expect wind monitoring and a plan for when to evacuate or take down, so keep records of the decisions made on the day.
Does marquee hire insurance cover tent and marquee erection for other hire firms?
Yes, contract erection can be covered. Insurers want to know who supplies the structure, who decides on anchoring and whether you inspect it before handover. Your liability may differ from the hire firm's, so contracts need clear responsibilities.
Is our stock covered while it is out on hire?
It can be, with all risks cover for stock away from your premises. Dry hire stock in a hirer's hands may need a specific section, and many firms also make hirers responsible for damage in their hire terms.
What if a stake hits a buried pipe or cable?
Damage to underground services is usually covered under public liability, but some insurers apply conditions on checking for services before staking. Asking clients about buried pipes and cables, and recording the answer, protects you.
Are heaters and generators we supply covered?
They can be, but declare them. Gas heaters and generators add fire, fume and products risks, and insurers may ask about servicing, siting and safety checks before each hire.
Does the policy cover lost bookings if the weather cancels an event?
No. Your liability and stock cover does not pay when weather calls an event off. Organisers buy event cancellation cover for that, and your hire terms decide whether deposits are kept.
Do we need different cover for structures used as temporary warehouses?
Declare them. Long-term structures used for storage or industrial work stand through winter storms and snow, so insurers treat them differently from event marquees that are up for a few days.
How do I get a marquee hire insurance quote?
Begin with the enquiry form here. A broker working with our partner will then phone to talk through your structures. Sizes and types, stock values, crew numbers, weather procedures, vehicles and claims history are the essentials.
Compare marquee hire insurance
Liability, stock and crew cover for firms whose structures shelter guests in all weathers.