Painters and Decorators Insurance for decorating contractors
Painters and decorators insurance for decorating firms with painting teams on housing, commercial and maintenance contracts. Compare cover that reflects how much you spray, how high you work and what you strip back.
- Liability for spills, overspray and heat work fires
- Employers' liability for painters and labourers
- Spray kit, towers and paint stock covered
Reviewed October 2026 by the MyBusinessComparison.com editorial team
What is painters and decorators insurance?
Painters and decorators insurance is cover for decorating firms that prepare and finish surfaces in homes, offices and commercial buildings. It brings together public liability for paint spills, overspray and fire, employers' liability for painters working at height, and cover for spray equipment, access towers and materials.
Decorating looks low risk until something goes wrong in someone else's building. A tin knocked over on new carpet, overspray drifting onto cars in a car park, or a blowlamp setting fire to a roof void are typical claims. Preparing older surfaces brings dust from lead paint and, in some properties, textured coatings that may contain asbestos.
Insurers ask how your work splits between interior and exterior, how much is sprayed, your highest working level and whether you apply specialist coatings such as intumescent paint, floor coatings or industrial finishes on steelwork.
Painters and decorators insurance at a glance
- Suits
- Decorating firms with employed painters on housing, commercial and maintenance work
- Core covers
- Public liability with employers' liability
- Often added
- Contract works, spray equipment, access towers, tools and paint stock
- Insurers ask about
- Spraying, burning off, working height, lead paint and asbestos checks
- Priced on
- Wage roll, turnover, exterior and height work, specialist coatings, claims
- Separate cover
- Vans on a commercial vehicle policy
What does painters and decorators insurance cover?
Decorating firms usually combine the sections below. Spraying, heat work and specialist coatings can each change the terms, so they need to be on the proposal.
Spills and drops
Spills on carpets and stone floors, paint on furniture and fittings, and a passer-by hurt by a tin or scraper dropped from a scaffold.
Read more about public liability insurance
Overspray damage
Fine paint mist carried on the wind onto parked cars, neighbouring buildings or a client's stock, a familiar claim for firms spraying exteriors, car parks and steelwork.
Heat work and fire
Stripping paint with blowlamps or heat guns is a known cause of fires in roof voids and timber frames, so most insurers allow it only under conditions, such as checking the area after work stops.
Painters at height
Falls from ladders, towers and cradles, effects of solvent exposure, and strain injuries among painters and labourers.
Read more about employers' liability insurance
Completed work
Problems after you leave, such as an anti-slip floor paint that wears through and someone falls, or intumescent coating applied too thin to give the fire protection specified.
Read more about completed work cover
Spray equipment and tools
Airless sprayers, extraction units, sanders, steamers and the paint stock carried in vans and held in store.
Read more about business equipment insurance
Access equipment
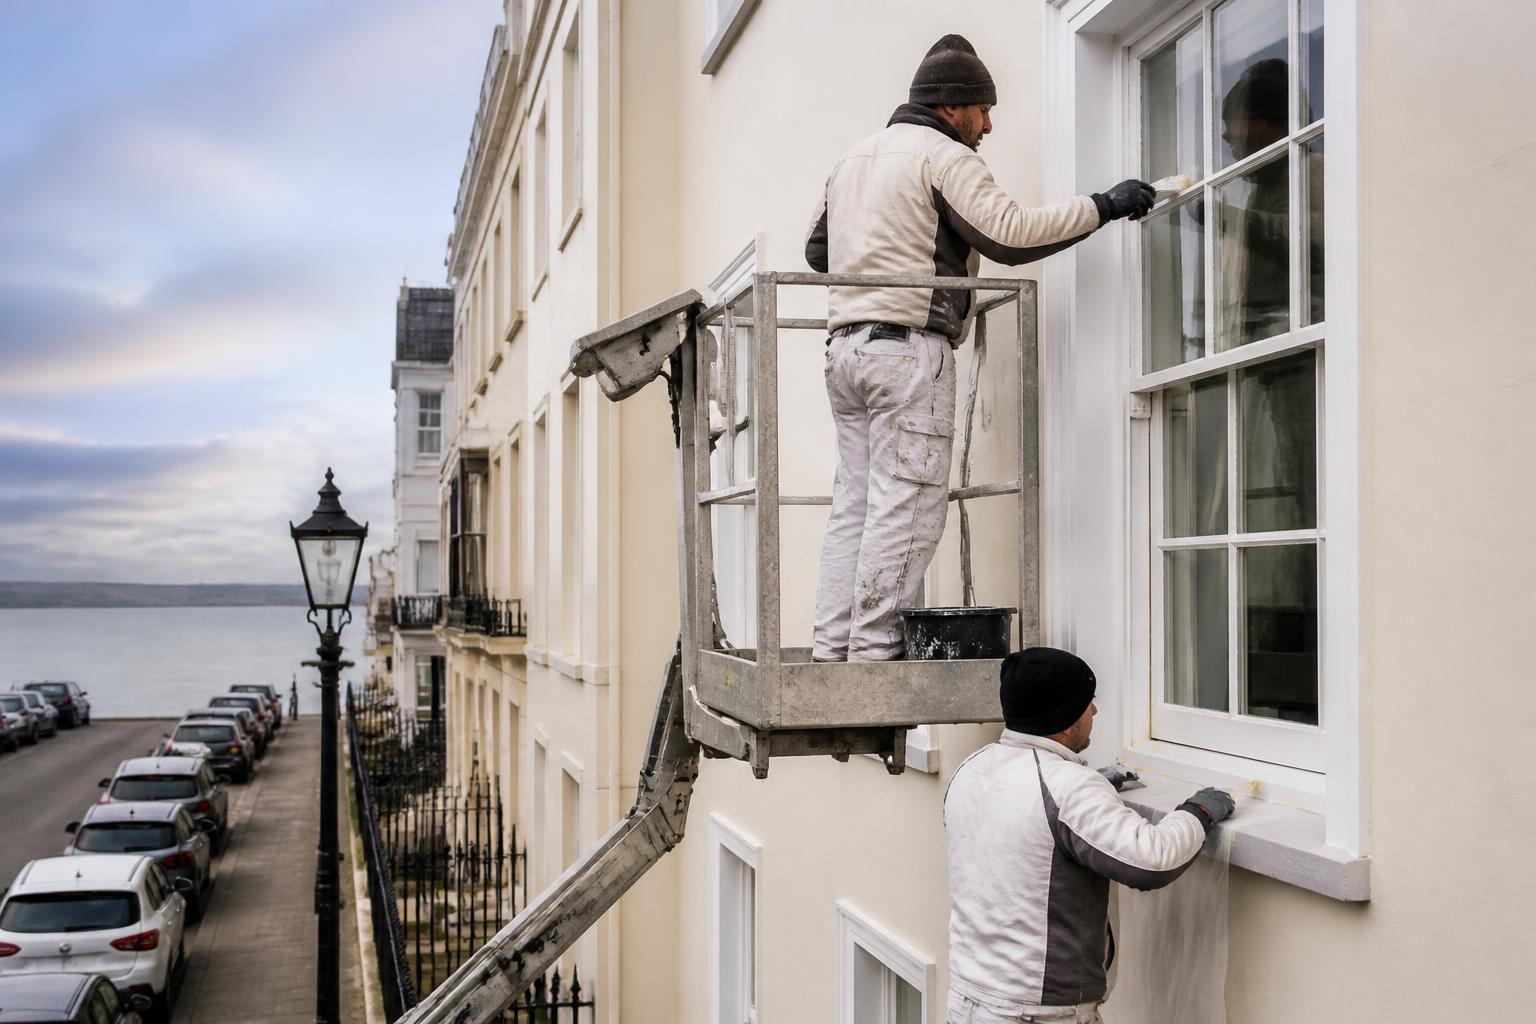
Owned and hired towers, podiums, cherry pickers and scissor lifts, with continuing hire charges if hired kit is damaged or stolen.
Read more about plant and machinery cover
Finished work before handover
Freshly finished work spoiled before handover by a break-in, vandalism, flood or another trade, where the contract leaves it at your risk.
Read more about contractors' all risks insurance
More cover decorating firms add
- Professional indemnity: for colour schemes, coating specifications and condition surveys on maintenance contracts
- Commercial legal expenses: disputes over snagging lists, retentions and late payment
- Group personal accident: a weekly benefit for painters off work after a fall
- Fleet insurance: decorating vans on one policy as the business grows
Which decorating businesses is this for?
Any established firm earning most of its turnover from preparing, painting and finishing surfaces, whether by brush, roller or spray gun.
Several trades under one roof? Firms offering decorating alongside plumbing, joinery and repairs can see property maintenance insurance, or browse the trades hub.
- Commercial decorating contractors: offices, schools, hospitals and retail units for main contractors and facilities managers
- New-build decorators: mist coats and final finishes across whole developments for house builders, often working to tight handover dates
- Domestic decorating firms: interior and exterior work in occupied homes, where contents, flooring and furniture drive most claims
- Spray painting contractors: airless spraying of walls, ceilings, cladding and joinery on site, where masking and wind control matter
- Industrial and protective coating firms: steelwork, tanks and plant in factories and depots, often at height and sometimes with blast cleaning
- Intumescent coating applicators: fire-protective paint on structural steel, where the dry film thickness must match the specification
- Artexing and textured finish firms: applying, patching and matching textured ceilings and walls, and skimming over older coatings once they have been tested
- Maintenance decorators: cyclical redecoration of flats, offices and communal areas for landlords, managing agents and housing providers
- Heritage decorators: traditional paints, limewash, gilding and graining in period and listed buildings
How much does painters and decorators insurance cost?
Decorating firms are rated on how they apply paint and where, as much as on their size. These factors usually decide the premium.
Spray or brush
The share of work that is sprayed changes the liability rating, because overspray can damage property well away from the job.
Exterior work and height
Painting from scaffold, cradles or powered access is rated above interior work, and insurers set a maximum height on the schedule.
Burning off
Whether you strip paint with heat, and the controls you follow, can decide whether fire damage is covered at all.
Specialist coatings
Intumescent, anti-slip floor and industrial coatings raise the completed work risk and may need declaring individually.
Wage roll
Employers' liability is rated on wages for employed painters and the cost of labour-only decorators working under your direction.
Claims history
Insurers weigh spill, overspray and fire claims, and want to know how your methods changed after each one.
What painters and decorators insurance does not cover
These are the exclusions decorating firms come up against most often.
- Redoing your own poor finish, runs, flaking paint or the wrong colour
- Fire caused by heat work where the conditions on your schedule were not followed
- Spraying that was not declared, as some trade policies exclude it altogether
- Asbestos in old textured coatings disturbed by sanding or scraping, beyond any limited extension
- Work above the height limit shown on your schedule
- Choosing or specifying coatings for a client, which needs professional indemnity
- Vans and their contents beyond the tools limit, with the vehicles themselves on a fleet policy
Brush and roller or spray application: how the risk changes
Many decorating firms do both. Insurers treat spraying as a different risk, so the share of work done each way needs to be stated clearly.
| Feature | Brush and roller | Spray application |
|---|---|---|
| Typical claims | Spills on floors and furniture, splashes on glass and stone | Overspray on cars, buildings and stock some distance from the job |
| Area at risk | The room or elevation being painted | Anything downwind or sharing the same air space |
| Controls insurers expect | Dust sheets and protection of floors and fittings | Full masking, wind checks, screening and exclusion zones |
| Risks to your painters | Ladder falls and manual handling | Mist inhalation, high-pressure injection injuries and noise |
| Rating | Standard decorating rate | Often rated higher, and must be declared |
How to compare painters and decorators insurance
Decorating risks are quoted faster when the broker has these details from the start.
Split your work
Interior and exterior, domestic and commercial, the share sprayed, and any specialist coatings.
Give heights and access
Your highest working level and the access used: ladders, towers, scaffold, cradles or powered access.
Explain any heat work
Whether you burn off paint, the tools used and the checks you carry out before leaving.
Set out the payroll
Employed painters, labour-only decorators and subcontractors who hold their own insurance.
Note claims and controls
Past claims, plus your asbestos checks, lead paint methods and how you mask and protect property.
Quotes for decorating firms
Describe your teams and typical contracts so a broker who covers finishing trades can compare terms.
Compare coverPainters and decorators insurance FAQs
How much does painters and decorators insurance cost?
Wage roll, turnover, the share of exterior and sprayed work, working height, any heat work or specialist coatings and your claims history set the price. A firm spraying industrial steelwork is rated very differently from one decorating offices by brush and roller.
Does painters and decorators insurance cover paint spilled on a client's carpet?
Usually, yes. Accidental damage to a client's property, such as paint on a carpet, sofa or stone floor, falls under public liability in most policies, less the excess. Insurers expect floors and furniture to be protected, and repeated small claims can affect renewal terms.
Is overspray onto cars covered?
Usually, if you declared spraying and followed the policy conditions. Overspray claims often involve several vehicles in a car park or street, so insurers ask about masking, screening and how you check wind before spraying exteriors.
Are we covered for burning off old paint?
Only if heat work is declared and the conditions are met. Many policies require a fire extinguisher on hand, no heat near roof voids or thatch, and a check of the area once work stops. Fires caused outside those conditions may not be paid.
Does it cover artexing and textured ceilings?
Applying and repairing textured finishes can be covered as part of decorating. Older textured coatings can contain asbestos, so sanding, scraping or removing them is a different matter: insurers expect testing first and specialist removal where asbestos is found.
What about lead paint in older buildings?
Preparing old painted surfaces can spread lead dust through a home. Insurers ask whether you test for lead and use wet methods rather than dry sanding or burning off. Check how your policy treats contamination claims, as some limit them.
Is intumescent paint covered by a standard decorating policy?
Not always. Intumescent coatings protect structural steel in a fire, and a coating applied too thin could contribute to a serious loss. Many insurers want it declared separately and may ask about training, inspection and how thickness is recorded.
What is the difference between decorators and plasterers insurance?
Decorating firms are rated on painting, spraying, heat work and coatings. Contractors who mainly plaster walls or apply render need plasterers insurance, and firms boarding and building partitions belong under dry lining insurance.
Are labour-only decorators covered by our employers' liability?
They can be, if you include their cost in your wage roll. Insurers generally treat labour-only decorators working under your direction like employees. Subcontractors who supply their own materials and hold their own insurance are rated differently, so keep copies of their certificates.
How do I get a painters and decorators insurance quote?
Open the quote form from this page, and a specialist in decorating risks will phone you. Useful details to have ready: your work split, maximum heights, spraying and heat work, payroll and claims history.
Ready to compare painters and decorators insurance?
Cover for decorating firms that reflects how you prepare, paint and spray, arranged by a broker who knows finishing trades.